Company Coverage
Tencent Holdings (700 HK): 3Q26 Preview: Clear AI Strategy; Investment Pressure On Margins
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$387.60
HK$537.00
38.5%
HK$608.00
Analyst
Highlights
- Tencent will report its 3Q26 results in mid-November. We expect Tencent’s revenue growth to remain solid at 9% yoy in 3Q26 despite macro headwinds, supported by stable gaming and resilient advertising driven by higher ad loads and improved eCPM. Operating profit is likely to remain flattish due to increased AI-related investment. We maintain overweight on Tencent, supported by resilient core franchises, attractive valuation and potential upside from Weixin AI agents.
- Maintain BUY with a lower target price of HK$537.00.
Analysis
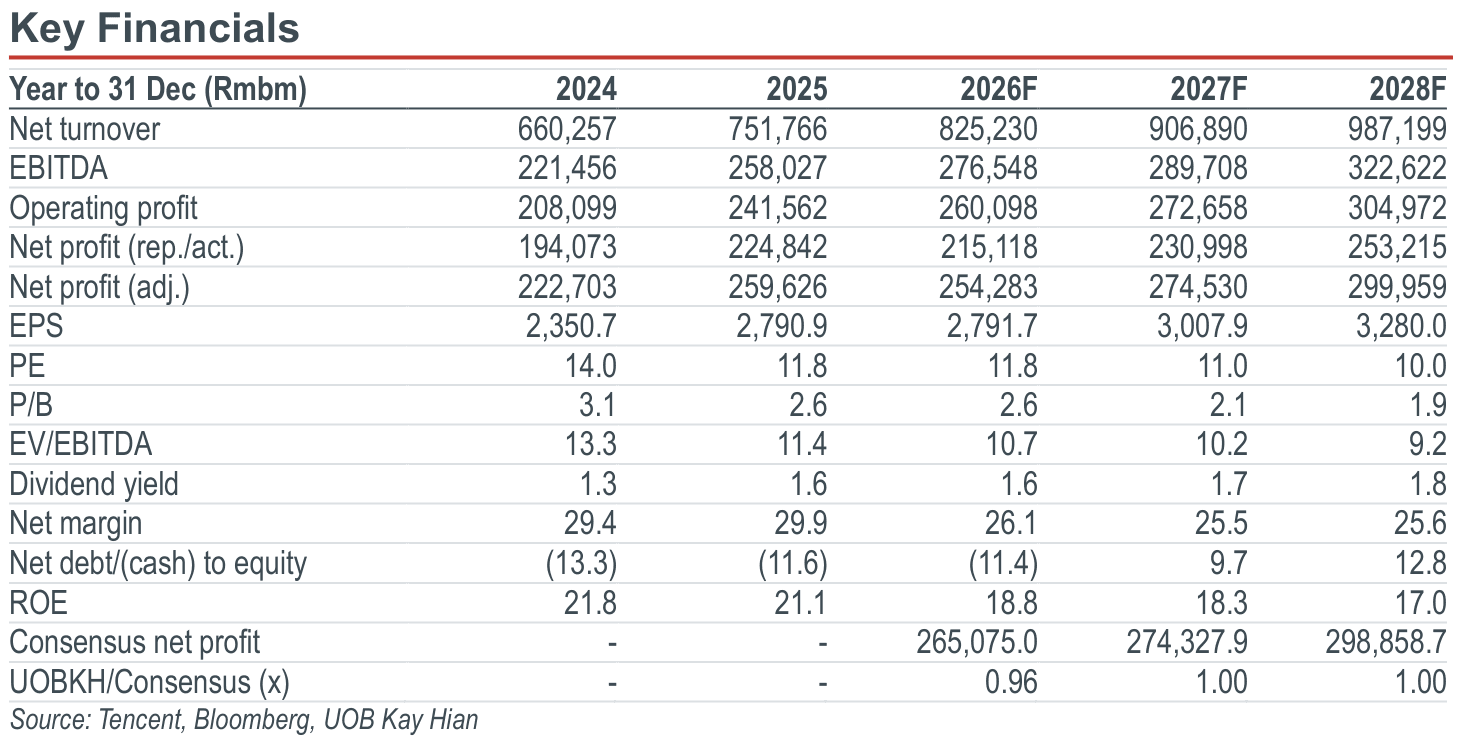
- Moderating 3Q26 game revenue growth due to high base effect. We forecast 3Q26 games revenue growing moderately to 6.7% yoy to Rmb67.8b due to the high base effect from international games in 3Q25, but supported by resilient evergreen titles and a solid new-game pipeline. For instance, Battle of Golden Shovel’s Mainland China iOS revenue rose 45% mom in September, driven by anniversary events, with the title ranking second on the iOS grossing chart on 30 September. Social network revenue could expand 5% to Rmb33.8b amid softer digital content demand. We expect Tencent's 3Q26 revenue to rise 9% yoy to Rmb210.8b, while adjusted operating profit should be flattish yoy at Rmb73.1b.
- Online marketing services to remain resilient. Advertising should remain a key growth driver; we project that 3Q26 marketing services revenue will increase 18% yoy to Rmb42.7b, moderating from 22% in 2Q26. Overall momentum remains resilient, underpinned by continued enhancements in AI-driven ad targeting precision, which is expected to support both monetisation efficiency and margin expansion.
- Tencent Cloud likely to continue its solid momentum. Fintech and business services revenue is expected to grow 9% yoy to Rmb63.4b, as improving cloud demand partly offsets softer consumption-related fintech activity. We forecast cloud revenue expanding 23% yoy to Rmb15.7b, to reflect incremental AI cloud and enterprise application monetisation.
- Clearer AI strategy, although rising AI investment could weigh on near-term earnings. We expect Tencent Holdings (Tencent) to prioritise monetisation through enterprise AI tools and cloud services, supported by faster iteration of its in-house models, before scaling AI agents within Weixin. While we remain positive on Tencent's AI ecosystem and distribution advantages, higher depreciation and inference costs are likely to precede meaningful revenue contribution. We foresee 3Q26/2026 adjusted net profit dropping 5% yoy and 2% yoy.
Highlights
- Tencent will report its 3Q26 results in mid-November. We expect Tencent’s revenue growth to remain solid at 9% yoy in 3Q26 despite macro headwinds, supported by stable gaming and resilient advertising driven by higher ad loads and improved eCPM. Operating profit is likely to remain flattish due to increased AI-related investment. We maintain overweight on Tencent, supported by resilient core franchises, attractive valuation and potential upside from Weixin AI agents.
- Maintain BUY with a lower target price of HK$537.00.
Analysis
- Moderating 3Q26 game revenue growth due to high base effect. We forecast 3Q26 games revenue growing moderately to 6.7% yoy to Rmb67.8b due to the high base effect from international games in 3Q25, but supported by resilient evergreen titles and a solid new-game pipeline. For instance, Battle of Golden Shovel’s Mainland China iOS revenue rose 45% mom in September, driven by anniversary events, with the title ranking second on the iOS grossing chart on 30 September. Social network revenue could expand 5% to Rmb33.8b amid softer digital content demand. We expect Tencent's 3Q26 revenue to rise 9% yoy to Rmb210.8b, while adjusted operating profit should be flattish yoy at Rmb73.1b.
- Online marketing services to remain resilient. Advertising should remain a key growth driver; we project that 3Q26 marketing services revenue will increase 18% yoy to Rmb42.7b, moderating from 22% in 2Q26. Overall momentum remains resilient, underpinned by continued enhancements in AI-driven ad targeting precision, which is expected to support both monetisation efficiency and margin expansion.
- Tencent Cloud likely to continue its solid momentum. Fintech and business services revenue is expected to grow 9% yoy to Rmb63.4b, as improving cloud demand partly offsets softer consumption-related fintech activity. We forecast cloud revenue expanding 23% yoy to Rmb15.7b, to reflect incremental AI cloud and enterprise application monetisation.
- Clearer AI strategy, although rising AI investment could weigh on near-term earnings. We expect Tencent Holdings (Tencent) to prioritise monetisation through enterprise AI tools and cloud services, supported by faster iteration of its in-house models, before scaling AI agents within Weixin. While we remain positive on Tencent's AI ecosystem and distribution advantages, higher depreciation and inference costs are likely to precede meaningful revenue contribution. We foresee 3Q26/2026 adjusted net profit dropping 5% yoy and 2% yoy.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$387.60
HK$537.00
38.5%
HK$608.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

21 Oct 2026
Lenovo Group (992 HK): 2QFY27 Results Preview: ISG To Register Another Quarter Of Strong Growth

21 Oct 2026
Alibaba Group (9988 HK): 2QFY27 Preview: Cloud Growth Accelerates; Losses Continue To Narrow

27 Oct 2026
ZTE Corporation (763 HK): 3Q26: Operating Profit Dragged Down By Weak Margins And High Operating Expenses
Our latest research

29 Oct 2026
ASMPT (522 HK): 3Q26: Record Bookings And SMT Strength Underpin Solid Outlook

29 Oct 2026
CSPC Innovation Pharmaceutical Co (300765 CH): 3Q26: Swings Back To A Net Loss; Late-Stage Pipeline Gathers Pace
29 Oct 2026