Company Coverage
ASMPT (522 HK): 3Q26: Record Bookings And SMT Strength Underpin Solid Outlook
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$118.30
HK$184.00
55.5%
HK$211.00
Analyst
Analyst
Highlights
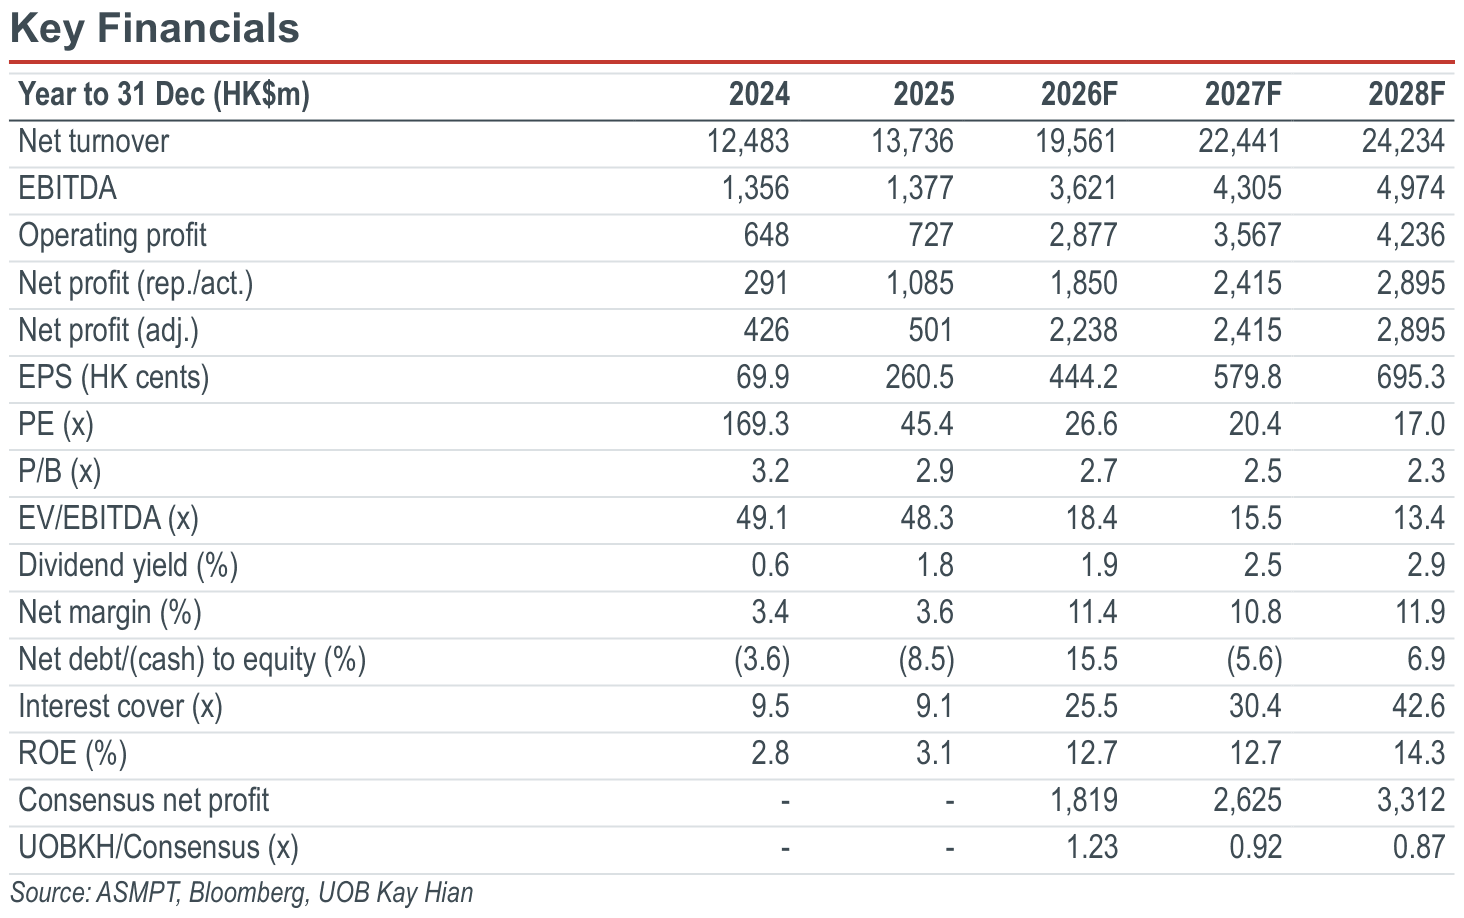
- Revenue and margins were solid, while share-based incentives weighed on reported net profit; record bookings provide a strong foundation for the subsequent quarters.
- Strong 4Q26 guidance suggests that robust SMT demand should offset delayed TCB revenue recognition.
- Maintain BUY with a target price of HK$184.00
Analysis
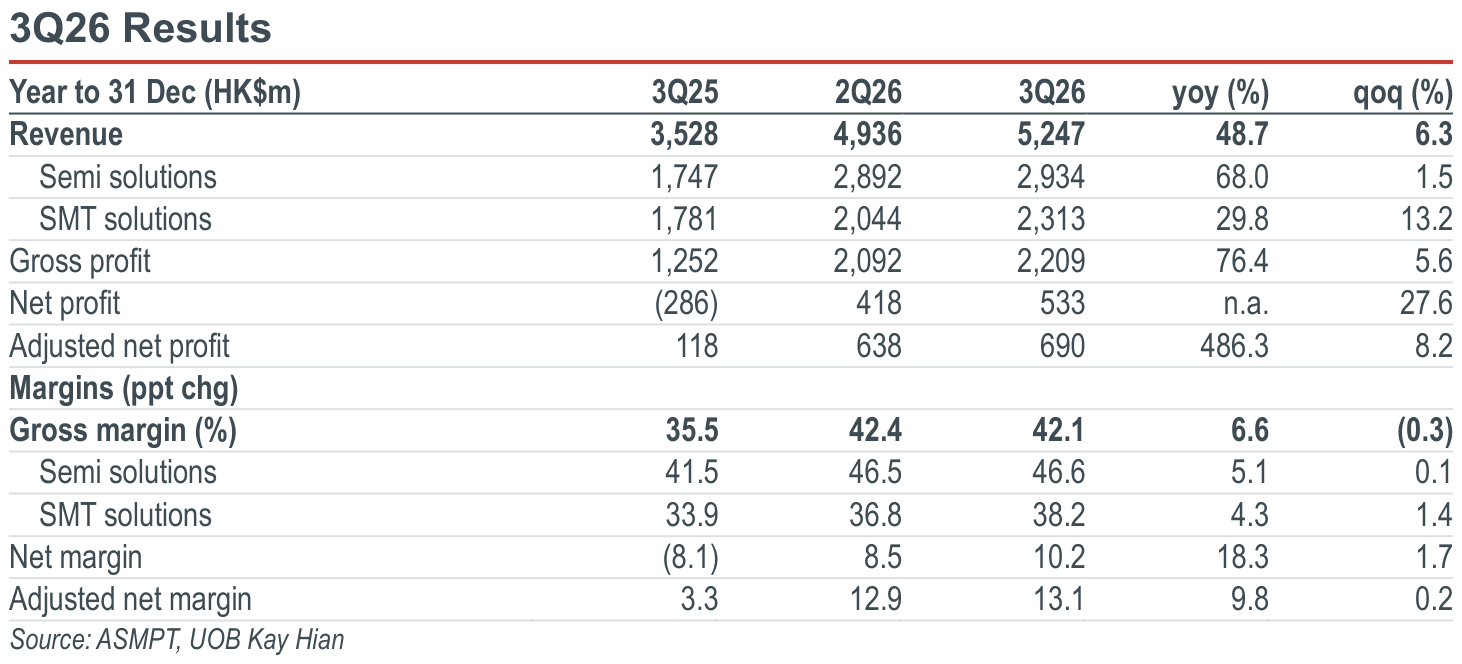
- Solid top-line and margins in 3Q26 while bottom line weighed by share-based payments. ASMPT’s 3Q26 revenue grew 48.7% yoy and 6.3% qoq to HK$5,247m, which is 3.8%/0.9% above our/consensus estimates. Gross margins expanded 6.6ppt yoy but moderated 0.3ppt qoq to 42.1%, which is a very slight beat to consensus. At the bottom line, a share-based incentives payment of HK$92.4m weighted on opex, which resulted in a slight miss on reported net profit which still turned around from a loss yoy and grew 27.6% qoq to HK$533m. Note that 3Q’s booking was exceptionally strong, growing 137.8% yoy and 24.7% qoq to HK$8,845m, which is the highest level since 2021 and the book-to-bill ratio continued to expand to 1.69x.
Highlights
- Revenue and margins were solid, while share-based incentives weighed on reported net profit; record bookings provide a strong foundation for the subsequent quarters.
- Strong 4Q26 guidance suggests that robust SMT demand should offset delayed TCB revenue recognition.
- Maintain BUY with a target price of HK$184.00
Analysis
- Solid top-line and margins in 3Q26 while bottom line weighed by share-based payments. ASMPT’s 3Q26 revenue grew 48.7% yoy and 6.3% qoq to HK$5,247m, which is 3.8%/0.9% above our/consensus estimates. Gross margins expanded 6.6ppt yoy but moderated 0.3ppt qoq to 42.1%, which is a very slight beat to consensus. At the bottom line, a share-based incentives payment of HK$92.4m weighted on opex, which resulted in a slight miss on reported net profit which still turned around from a loss yoy and grew 27.6% qoq to HK$533m. Note that 3Q’s booking was exceptionally strong, growing 137.8% yoy and 24.7% qoq to HK$8,845m, which is the highest level since 2021 and the book-to-bill ratio continued to expand to 1.69x.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$118.30
HK$184.00
55.5%
HK$211.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

23 Oct 2026
Han’s Laser (002008 CH): 3Q26: Strong Beat In IT Business

27 Oct 2026
ZTE Corporation (763 HK): 3Q26: Operating Profit Dragged Down By Weak Margins And High Operating Expenses

29 Oct 2026
Tencent Holdings (700 HK): 3Q26 Preview: Clear AI Strategy; Investment Pressure On Margins
Our latest research

29 Oct 2026
CSPC Innovation Pharmaceutical Co (300765 CH): 3Q26: Swings Back To A Net Loss; Late-Stage Pipeline Gathers Pace
29 Oct 2026
TA: H World Group (1179 HK) / China Overseas Land & Investment (0688 HK)

29 Oct 2026