Company Coverage
Lenovo Group (992 HK): 2QFY27 Results Preview: ISG To Register Another Quarter Of Strong Growth
BUY (Maintained)
Current price:
Target price:
Upside:
HK$25.26
HK$49.00
+94.0%
Analyst
Analyst
Highlights
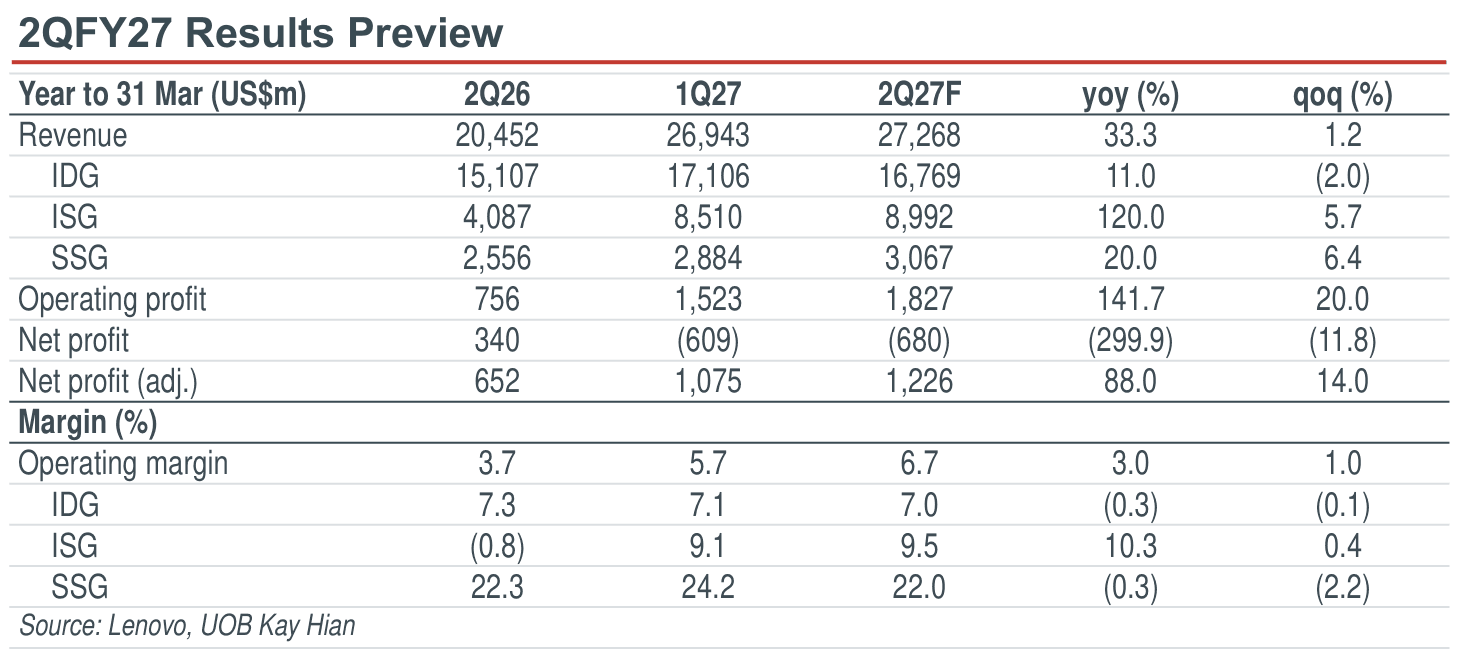
- We expect 2QFY27 non-IFRS net profit to grow 88% yoy to US$1,226m, primarily driven by robust 120% yoy revenue growth in the ISG business, and a resilient 11.0% yoy revenue growth in the IDG business.
- The non-cash fair value loss from the warrant issued alongside the ALAT CB is estimated to be US$1.9b. This will push reported net profit to a US$680m loss.
- Maintain BUY and target price of HK$49.00.
Analysis
- We are expecting strong print across the board. We expect 2QFY27 revenue of US$27,268m, +33.3% yoy and +1.2% qoq, adjusted operating margin of 6.7%, +3.0ppt yoy and +1.0ppt qoq, and core operating profit of US$1,827m, +20.0% yoy and 6.4% qoq. With Lenovo’s share price surging from HK$23.02 to HK$34.54 during the quarter, we are estimating a US$1.9b non-cash fair value loss due to its warrant issued along with the ALAT convertible bonds which have an adjusted strike price of HK$11.92. This will push reported net profit to a US$680m loss (vs 2Q26 profit at US$340m). Stripping that off, non-IFRS net profit is expected to surge 88.0% yoy and 14.0% qoq to US$1,226m.
Highlights
- We expect 2QFY27 non-IFRS net profit to grow 88% yoy to US$1,226m, primarily driven by robust 120% yoy revenue growth in the ISG business, and a resilient 11.0% yoy revenue growth in the IDG business.
- The non-cash fair value loss from the warrant issued alongside the ALAT CB is estimated to be US$1.9b. This will push reported net profit to a US$680m loss.
- Maintain BUY and target price of HK$49.00.
Analysis
- We are expecting strong print across the board. We expect 2QFY27 revenue of US$27,268m, +33.3% yoy and +1.2% qoq, adjusted operating margin of 6.7%, +3.0ppt yoy and +1.0ppt qoq, and core operating profit of US$1,827m, +20.0% yoy and 6.4% qoq. With Lenovo’s share price surging from HK$23.02 to HK$34.54 during the quarter, we are estimating a US$1.9b non-cash fair value loss due to its warrant issued along with the ALAT convertible bonds which have an adjusted strike price of HK$11.92. This will push reported net profit to a US$680m loss (vs 2Q26 profit at US$340m). Stripping that off, non-IFRS net profit is expected to surge 88.0% yoy and 14.0% qoq to US$1,226m.
BUY (Maintained)
Current price:
Target price:
Upside:
HK$25.26
HK$49.00
+94.0%
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

21 Oct 2026
Alibaba Group (9988 HK): 2QFY27 Preview: Cloud Growth Accelerates; Losses Continue To Narrow

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

21 Sept 2026
Alibaba Health Information Technology (241 HK): 1HFY27 Preview: Lowers FY27 Revenue Growth Target To 7-10% yoy On Subsidy Optimisation; Earnings Guidance Unchanged
Our latest research
21 Oct 2026
TA: CK Asset (1113 HK) / Nongfu Spring (9633 HK)
21 Oct 2026
Alibaba Group (9988 HK): 2QFY27 Preview: Cloud Growth Accelerates; Losses Continue To Narrow

21 Oct 2026