Company Coverage
Tsingtao Brewery (168 HK): 3Q26: Net Profit Down 17%; Sales Volume Down 9%; ASP Up 4%
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$38.80
HK$55.50
+43.0%
HK$62.40
Analyst
Analyst
Highlights
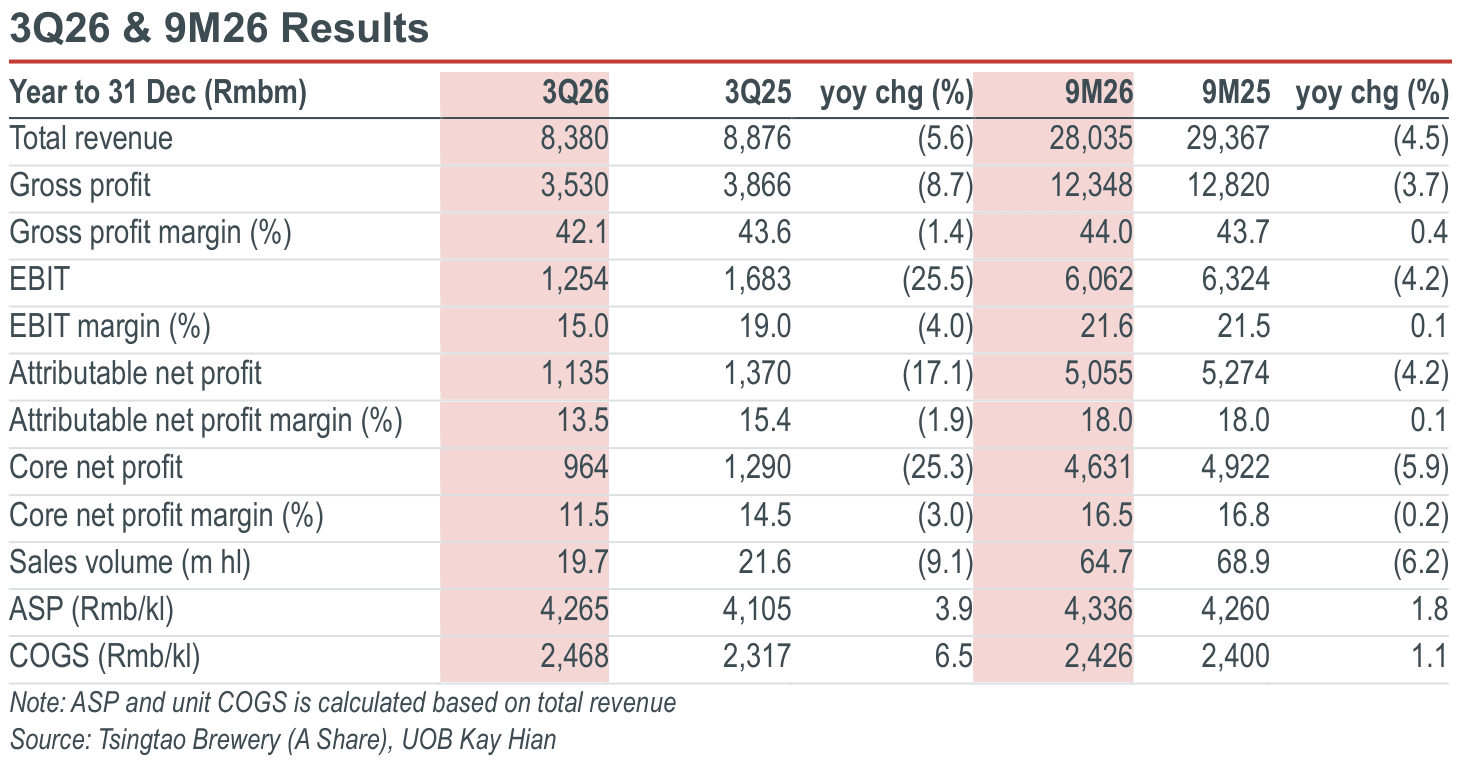
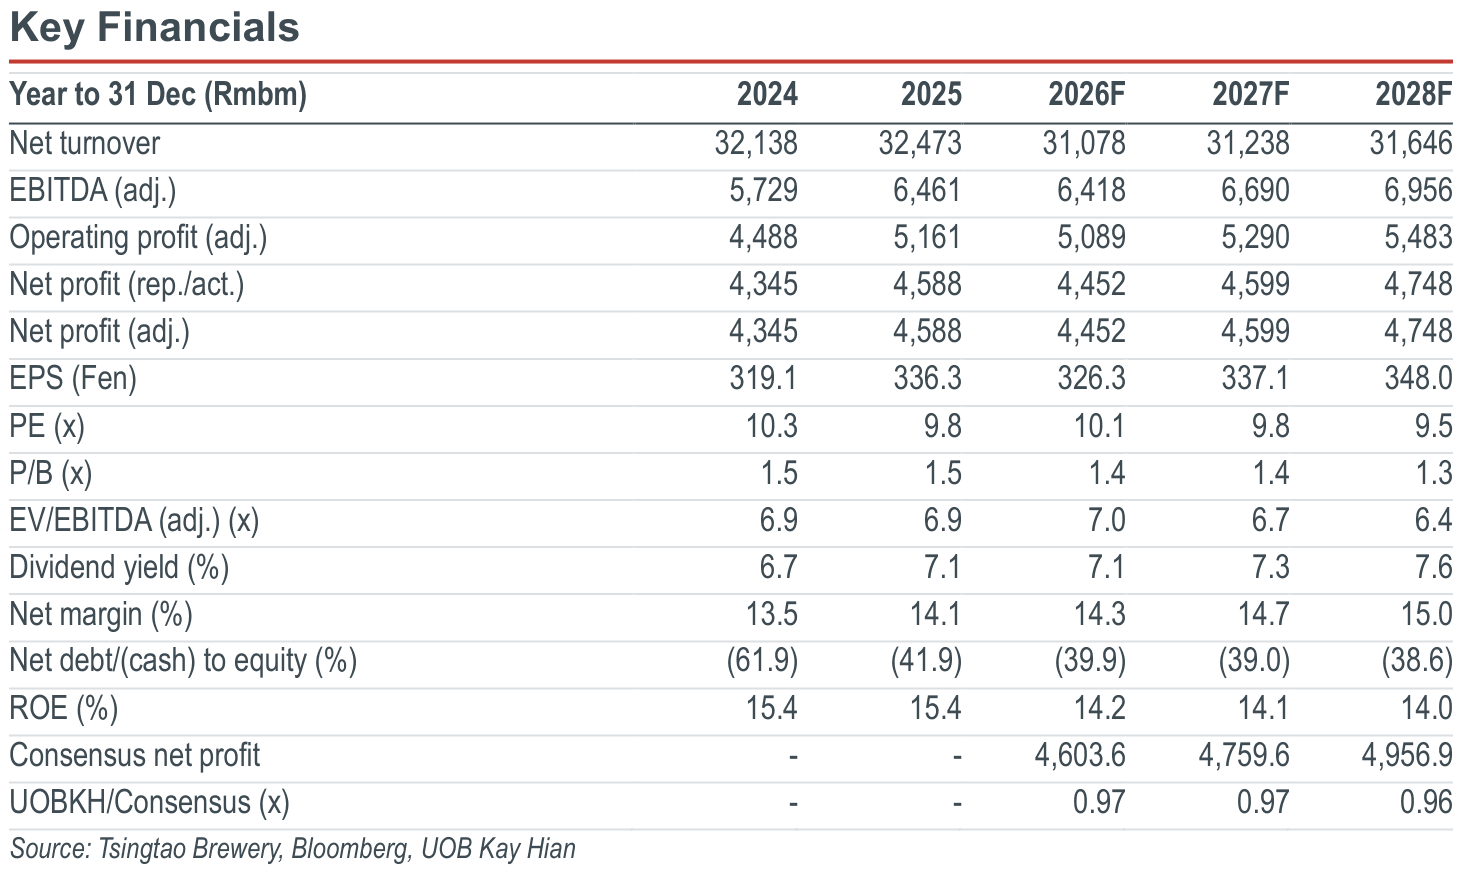
- Tsingtao Brewery’s 3Q26 net profit fell 17% yoy, primarily due to a decline in revenue, driven by lower sales volume yet partially offset by ASP increase, as well as gross margin contraction amid rising unit COGS and higher SG&A expenses.
- 3Q26 sales volume was 19.7m hl, down 9% yoy. By brand, sales volume of the Tsingtao brand and secondary brand declined 3% and 18% yoy, respectively. By category, sales volume of mid-range to high-end products increased 1% yoy, while that of other products dropped 17% yoy.
- Maintain BUY, cut target price by 11% to HK$55.50.
Analysis
- 3Q26 net profit fell 17% yoy. Tsingtao Brewery reported 9M26 revenue of Rmb28,035m (-5% yoy). Gross margin was 44.0% (+0.4ppt yoy). EBIT totalled Rmb6,062m (-4% yoy), and EBIT margin was 21.6% (+0.1ppt yoy). Net profit was Rmb5,055m (-4% yoy), and net margin was 18.0% (+0.1ppt yoy).
Highlights
- Tsingtao Brewery’s 3Q26 net profit fell 17% yoy, primarily due to a decline in revenue, driven by lower sales volume yet partially offset by ASP increase, as well as gross margin contraction amid rising unit COGS and higher SG&A expenses.
- 3Q26 sales volume was 19.7m hl, down 9% yoy. By brand, sales volume of the Tsingtao brand and secondary brand declined 3% and 18% yoy, respectively. By category, sales volume of mid-range to high-end products increased 1% yoy, while that of other products dropped 17% yoy.
- Maintain BUY, cut target price by 11% to HK$55.50.
Analysis
- 3Q26 net profit fell 17% yoy. Tsingtao Brewery reported 9M26 revenue of Rmb28,035m (-5% yoy). Gross margin was 44.0% (+0.4ppt yoy). EBIT totalled Rmb6,062m (-4% yoy), and EBIT margin was 21.6% (+0.1ppt yoy). Net profit was Rmb5,055m (-4% yoy), and net margin was 18.0% (+0.1ppt yoy).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$38.80
HK$55.50
+43.0%
HK$62.40
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

28 Oct 2026
Wuliangye Yibin (000858 CH): 3Q26: Net Profit Declines Sharply Declines Despite A Revised Base; Downgrade To SELL

27 Oct 2026
ZTE Corporation (763 HK): 3Q26: Operating Profit Dragged Down By Weak Margins And High Operating Expenses

22 Oct 2026
Fuyao Glass (3606 HK): 3Q26: Earnings Dragged By Higher Sea Freight Costs And One-off Expenses; Cut Target Price To HK$77.00
Our latest research

29 Oct 2026
ASMPT (522 HK): 3Q26: Record Bookings And SMT Strength Underpin Solid Outlook

29 Oct 2026
CSPC Innovation Pharmaceutical Co (300765 CH): 3Q26: Swings Back To A Net Loss; Late-Stage Pipeline Gathers Pace
29 Oct 2026