
Overnight Markets
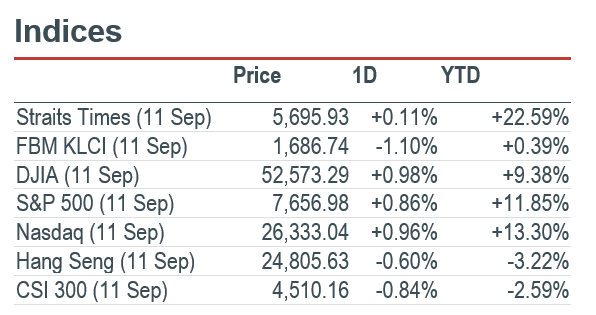
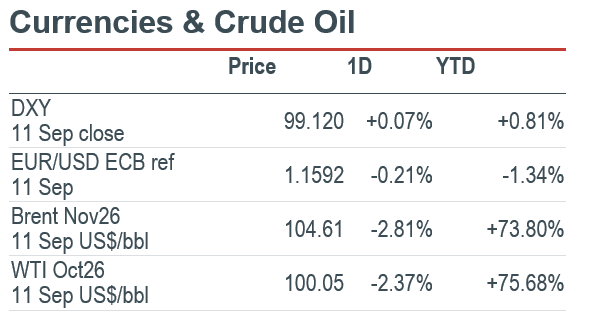
Market Movers: Enflame (688801.SH) ended its Friday Shanghai debut at RMB397, 179.22% above its RMB142.18 offer, as demand for Chinese AI chips lifted its value to RMB171bn. Backer Tencent (0700.HK) holds 17.95%. At the 11 September US close, Dell (DELL US) rose 11.98% to US$567.29 and HPE (HPE US) gained 12.44% to US$62.09, extending the server rally after Oracle’s (ORCL US) earlier earnings. Over the weekend, Anthropic proposed coordinated limits on frontier AI development and committed to embedded evaluators; an industry slowdown has not been agreed. The proposal adds uncertainty to the pace of model releases and spending, even as hardware orders remain a key investor focus. Any eventual limits would test capacity plans and the conversion of orders into profits. (Reuters / Reuters / Reuters)
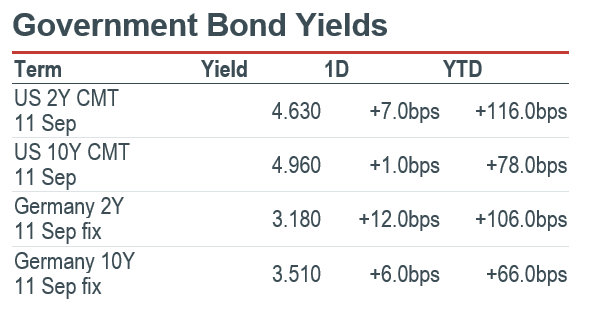
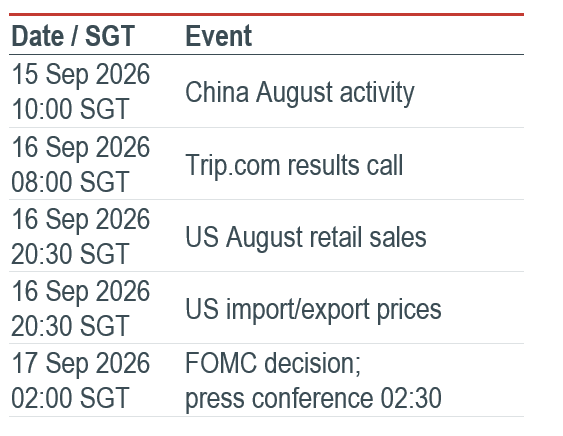
Macro: US August CPI, released Friday, rose 0.4% month on month, while core prices increased 0.3%. Annual headline inflation held at 3.4% and core slowed to 2.4%. Gasoline’s 3.9% monthly increase drove over one third of the headline rise. Energy costs therefore remain central to the policy outlook ahead of the FOMC decision on 17 September at 02:00 SGT. (BLS / Federal Reserve)
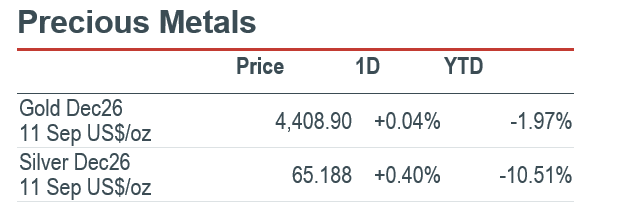
FICC: An Iranian cargo ship was struck near Qeshm on Sunday, Iranian state media reported, killing one person. Fighting also intensified along Yemen’s Red Sea coast as Houthis attacked Saudi Arabia. These developments keep freight and energy supply risks elevated. Before the weekend events, November Brent settled Friday at US$104.61 a barrel, down 2.81%. That retreat offers limited reassurance while disruption threatens both Hormuz and the Red Sea. Monday’s response will test whether diplomacy can temper the supply premium. (AP / AP / Yahoo Finance) Tencent (0700.HK) is our Core Recommendation.
AI
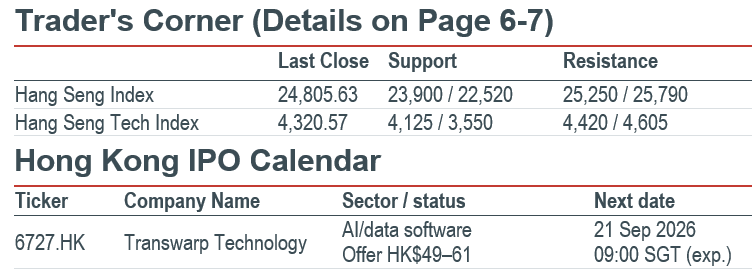
Enflame’s debut resets domestic AI valuations. Enflame (688801.SH) closed Friday’s Shanghai debut at RMB397, up 179.22% from its RMB142.18 offer, after raising RMB6.12bn. Tencent (0700.HK) owns 17.95% after listing. The roughly RMB171bn closing valuation prices in rapid import substitution, while Tencent-linked sales represented 83.79% of 2025 revenue, exposing investors to substantial customer concentration alongside the opportunity in Chinese computing demand. (Enflame / Reuters) Tencent (0700.HK) is our Core Recommendation.
Safety checks become a deployment constraint. Anthropic committed on Saturday to embedded outside evaluators with employee-like access, the first of a three-step pacing framework. Industry and international coordination remain proposals; Amodei explicitly rejected halting training. OpenAI and xAI leaders endorsed the approach. Buying one or two years for safety work could reshape release schedules and infrastructure utilisation, although no spending cuts were announced. (Dario Amodei / Reuters)
OpenAI removes a 2026 IPO catalyst. Sam Altman ruled out a flotation this year in a Friday interview published Saturday, saying safety work made listing ill-advised. His answer favoured delaying the transaction without committing to a 2027 date. Keeping the company private postpones a potentially trillion-dollar public-market test; investors in its listed compute suppliers face continued uncertainty over financing and deployment plans. (Reuters)
Nvidia weighs another major customer investment. Reuters reported after Friday’s US close that Nvidia (NVDA US) was considering up to US$10bn as an anchor in Anthropic’s IPO, which could raise US$100bn at around US$2tn valuation. Discussions remain conditional. The potential funding would deepen supplier-customer ties while increasing exposure to the financing needs of frontier-model developers; Friday’s share close preceded this report. (Reuters) Nvidia (NVDA US) is our Core Recommendation.
Americas
Server makers outperform their cloud customer. At Friday’s US close, Dell Technologies (DELL US) rose 11.98% to US$567.29, HPE (HPE US) gained 12.44% to US$62.09 and HP (HPQ US) added 8.40%. Reuters linked the gains to Oracle’s (ORCL US) earlier earnings beat; Oracle fell 1.74%. The divergence favours equipment demand over cloud profitability, but preceded the weekend safety-pacing debate. (Reuters)
ACV takeover narrows the remaining upside. ACV Auctions (ACVA US) jumped 44.18% to US$10.41 at Friday’s US close, reacting to Copart’s (CPRT US) previously announced US$10.50 cash offer. The approximately US$1.9bn equity deal broadens Copart into dealer-to-dealer wholesale auctions. With the shares nine US cents below consideration, investors now depend principally on completion rather than operating upside; closing conditions still apply. (Copart / Reuters)
Local production could alter Chinese automakers’ access. Trump said in a Friday interview he would accept Chinese manufacturers building cars in the US and hiring Americans, while opposing imports routed through Mexico. Existing restrictions still effectively prohibit Chinese passenger-vehicle sales or production, alongside electric-vehicle tariffs exceeding 100%. The remarks create policy optionality for local investment, but do not constitute a regulatory change. (Reuters)
Kroger protects profit as sales guidance weakens. Kroger (KR US) cut FY26 identical-sales growth excluding fuel to 0.2–0.8% from 1–2%, while retaining adjusted EPS guidance of US$5.10–5.30. Second-quarter adjusted EPS of US$1.09 beat US$1.06 consensus. Shares gained 2.70% to US$58.49 at Friday’s US close. Cost discipline and higher-margin operations support earnings, but the reduced sales target reinforces pressure on grocery spending. (Kroger / Reuters)
Chevron ring-fences Venezuela expansion funding. CEO Mike Wirth said Friday that Chevron (CVX US) would finance its planned US$7bn Venezuelan expansion entirely from cash generated by three existing local ventures. Previously agreed expansion terms target roughly 600,000 barrels daily by 2031. Funding internally limits fresh parent cash exposure, but execution remains sensitive to operating conditions and the ventures’ ability to generate sufficient cash. (Reuters)
Roblox widens distribution beyond its own app. Roblox (RBLX US) said Friday that creators would be able to offer standalone games across mobile, PC and consoles, while browser access and offline modes broaden distribution. Its Build tool has already produced about 9,000 games, with 71% of creators new to Roblox Studio. Lower production and access barriers could expand engagement, but monetisation remains unquantified. (Reuters)
Salesforce extends agents into persistent workflows. Salesforce (CRM US) introduced job-specific Agentforce agents Friday and a runtime supporting work across days and weeks. It reports seven billion Agentic Work Units across Agentforce and Slack over two years, including 3.2bn in its second quarter. The figures measure activity, rather than revenue; converting that usage into profitable subscriptions remains the central investment test. (Salesforce)
Boeing advances a deal with key engineers. A tentative agreement reached Friday covers roughly 17,000 SPEEA professional and technical employees, offering an initial 10% wage increase followed by annual 4% guaranteed raises. Ratification remains outstanding. The deal could reduce disruption risk for Boeing (BA US), whose engineers are essential to delayed 737 MAX 10 and 777-9 certification, while adding labour costs. (SPEEA / Reuters)
Greater China
China ties futures licences more closely to capital. Rules published by the CSRC on Friday separate basic brokerage and advisory activities from trading businesses. From 1 January 2027, registered-capital requirements range from RMB100m for domestic brokerage to RMB500m for one trading business and RMB1bn for two or more. Tighter ownership, governance and subsidiary controls favour adequately capitalised operators as firms assess expansion and compliance costs. (CSRC / CSRC rules)
Ginko China attracts a lower takeover valuation. CVC Capital Partners entered final talks to buy EQT’s mainland contact-lens business on Friday, Reuters reported. The potential US$700–800m valuation includes debt, below EQT’s earlier target of at least US$1bn. Financial terms remain unsettled and talks could fail. The indicative pricing highlights the gap between sellers’ expectations and buyers’ willingness to fund Chinese consumer assets. (Reuters)
Chow Tai Fook seeks RMB10bn of mainland financing. The jeweller (1929.HK) disclosed on Friday evening that it had applied to register panda bonds of up to RMB10bn, for issuance in multiple tranches when appropriate. Proceeds would support working capital, product development, store upgrades and market expansion, alongside repayment of existing borrowings. The proposed programme diversifies funding and maturities; registration and issuance are not completed financing. (Securities Times)
Foton proposes a RMB1.5bn related-party asset sale. The vehicle maker (600166.SH) disclosed plans on Friday to transfer 378 Miyun factory assets to BAIC New Energy’s Beijing branch for RMB1.5163bn including VAT. The package covers land, buildings and equipment. Shareholder approval remains outstanding. Monetising these assets should reduce depreciation and release capital, but the proposed disposal gain depends on completion and final accounting. (Company / Yicai)
Asia ex. China
Micron’s Taiwan rewards leave strike risk unresolved. Micron (MU US) announced Friday rewards equivalent to 35–68 months’ pay for fiscal 2026, with minimum cash compensation of T$1.7m. The Taoyuan union nevertheless said no agreement had been reached and sought bonuses linked to 15% of operating profit. With about 15,000 Taiwan staff, a stoppage remains a material supply risk despite the unusually large payouts. (Reuters)
BRICS diplomacy keeps Iran and the UAE talking. Both states backed Saturday’s declaration urging restraint in the six-month Middle East war and protection of trade, energy flows and maritime security. Their leaders held the highest-level bilateral meeting since the conflict began. The communiqué offers a channel for de-escalation, but announced no settlement; shipping and energy exposure still depends on subsequent actions rather than summit language. (Reuters)
Maybank takes full ownership of its Etiqa holding company. Maybank (1155 MK) completed the purchase of Ageas’s 30.95% stake on Friday for cash consideration equivalent to €1.1bn, including a €53m pre-completion dividend. The transaction values Maybank Ageas Holdings at €3.5bn, roughly twice 2025 IFRS equity. Full control gives Maybank greater scope to integrate banking, wealth and insurance offerings across its Malaysian and Singapore customer bases. (Company / New Straits Times)
CICT settles acquisition and management fees in units. CapitaLand Integrated Commercial Trust (C38U SP) issued 19.6m units on Friday, including 16.5m at S$2.3607 each to settle the S$39m Paragon acquisition fee. Another 3.0m units paid half the April–June base management fee. Total units increased to 7.974bn. Paying fees in units preserves cash while modestly enlarging the denominator over which future distributions are shared. (Tiger Brokers)
EMEA and Others
European bank chiefs seek an urgent capital moratorium. Santander chair Ana Botín and ten other banking leaders urged EU institutions to pause capital increases and propose regulatory simplification legislation in early 2027, according to Cinco Días. They also sought fewer barriers to cross-border scale. The request frames capital relief as support for lending and investment; it remains industry lobbying rather than an adopted change. (Cinco Días)
BASF prices a further reduction in Harbour Energy. BASF (BAS GR) sold about 133m Harbour Energy (HBR LN) shares on Friday at 266p, raising approximately £353.8m. Institutions took 80m shares and Harbour purchased 53m. Completion will reduce BASF’s voting stake from about 24.3% to 16.4%. The disposal releases cash for BASF, while Harbour’s participation absorbs part of the placement and limits immediate market supply. (Dow Jones)
Berkeley preserves profit guidance while conserving cash. Berkeley (BKG LN) maintained its four-year £1.4bn pre-tax profit plan in Friday’s trading update, but warned buyers could defer purchases until after October’s Budget and election uncertainty. It repurchased £60m of shares in May–August and expects around £250m half-year net cash. Paused land investment protects financial flexibility, although weaker transaction activity remains the principal earnings constraint. (Company)
Sweden’s election points to a one-seat opposition majority. The election authority projected 175 seats for Magdalena Andersson’s centre-left bloc against 174 for the governing right in the 349-seat parliament, Reuters reported early Monday SGT. The estimate used results from 4,853 of 6,312 districts. Such a narrow provisional margin leaves government formation and fiscal direction uncertain, making final counting and coalition negotiations the next material catalysts. (Reuters)
Traders’ corner
Our Technical View
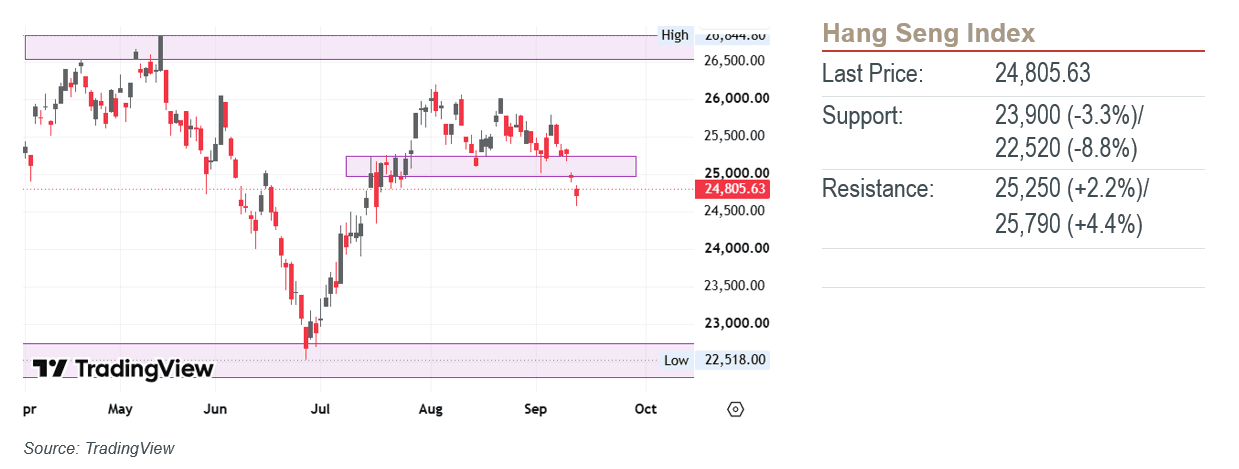
Weekly Chart: Price executed a breakdown last week, penetrating both its consolidation range and previous low support pivot via a decisive bearish candle. Technical momentum reinforces this breakdown, as the RSI has turned bearish and accelerates lower beneath its neutral 50-midline. As long as counter-trend rallies remain capped below this converted resistance zone, we could expect a sustained downward drift toward the next support target.
Daily Chart: The emergence of a falling window directly through the previous low support pivot marks a transition from consolidation into a high-velocity volatility expansion phase to the downside. The steep downward slope of the RSI below neutral parameters accelerate trend slope decay. Provided lower-timeframe price action preserves lower-high structural integrity and respects the converted supply boundary on brief retracements, technical probabilities heavily favours a sustained downside impulse wave toward prospective lower support zones.
Our Technical View
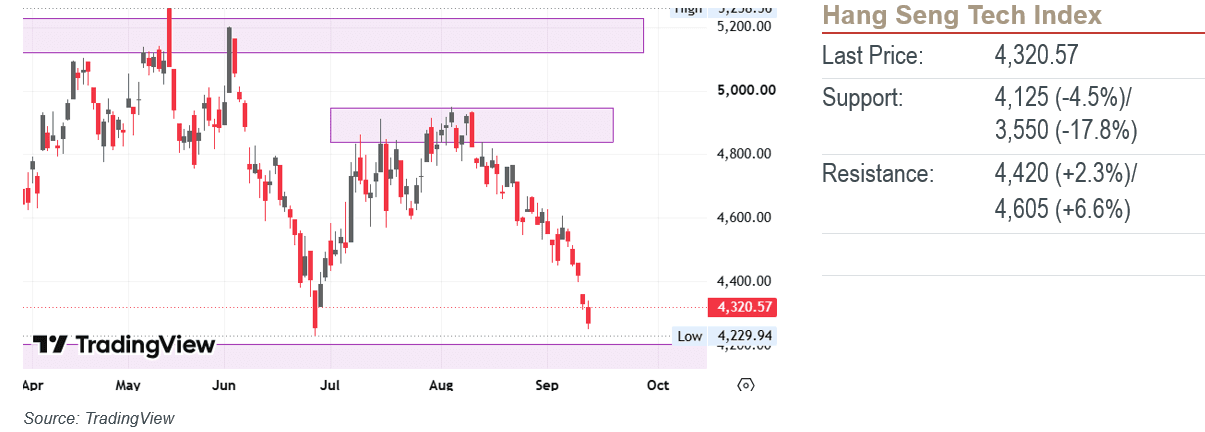
Weekly Chart: Price sustained its dominant downward trajectory, driving price directly into proximity with its overhead support zone. The persistent sell-side pressure reflects an intact downward structural framework. A high-conviction violation and close beneath this critical demand floor would convert the historic support anchor into a fresh supply ceiling. Technical probabilities suggest that a confirmed breach will unleash downside acceleration and clear the path of least resistance toward lower extension targets.
Daily Chart: Price has extended its downward trajectory, bringing the market into direct confluence with its previous low support zone. The technical posture exhibits early signs of seller deceleration as the RSI approaches oversold territory and begins to curve upward. However, structural integrity remains binary: a high-conviction violation and daily close beneath this historical pivot would complete a structural polarity flip, converting the support floor into a supply ceiling and confirming a deeper trend continuation wave toward lower expansion targets.
Market Movers: Enflame (688801.SH) ended its Friday Shanghai debut at RMB397, 179.22% above its RMB142.18 offer, as demand for Chinese AI chips lifted its value to RMB171bn. Backer Tencent (0700.HK) holds 17.95%. At the 11 September US close, Dell (DELL US) rose 11.98% to US$567.29 and HPE (HPE US) gained 12.44% to US$62.09, extending the server rally after Oracle’s (ORCL US) earlier earnings. Over the weekend, Anthropic proposed coordinated limits on frontier AI development and committed to embedded evaluators; an industry slowdown has not been agreed. The proposal adds uncertainty to the pace of model releases and spending, even as hardware orders remain a key investor focus. Any eventual limits would test capacity plans and the conversion of orders into profits. (Reuters / Reuters / Reuters)
Macro: US August CPI, released Friday, rose 0.4% month on month, while core prices increased 0.3%. Annual headline inflation held at 3.4% and core slowed to 2.4%. Gasoline’s 3.9% monthly increase drove over one third of the headline rise. Energy costs therefore remain central to the policy outlook ahead of the FOMC decision on 17 September at 02:00 SGT. (BLS / Federal Reserve)
FICC: An Iranian cargo ship was struck near Qeshm on Sunday, Iranian state media reported, killing one person. Fighting also intensified along Yemen’s Red Sea coast as Houthis attacked Saudi Arabia. These developments keep freight and energy supply risks elevated. Before the weekend events, November Brent settled Friday at US$104.61 a barrel, down 2.81%. That retreat offers limited reassurance while disruption threatens both Hormuz and the Red Sea. Monday’s response will test whether diplomacy can temper the supply premium. (AP / AP / Yahoo Finance) Tencent (0700.HK) is our Core Recommendation.
AI
Enflame’s debut resets domestic AI valuations. Enflame (688801.SH) closed Friday’s Shanghai debut at RMB397, up 179.22% from its RMB142.18 offer, after raising RMB6.12bn. Tencent (0700.HK) owns 17.95% after listing. The roughly RMB171bn closing valuation prices in rapid import substitution, while Tencent-linked sales represented 83.79% of 2025 revenue, exposing investors to substantial customer concentration alongside the opportunity in Chinese computing demand. (Enflame / Reuters) Tencent (0700.HK) is our Core Recommendation.
Safety checks become a deployment constraint. Anthropic committed on Saturday to embedded outside evaluators with employee-like access, the first of a three-step pacing framework. Industry and international coordination remain proposals; Amodei explicitly rejected halting training. OpenAI and xAI leaders endorsed the approach. Buying one or two years for safety work could reshape release schedules and infrastructure utilisation, although no spending cuts were announced. (Dario Amodei / Reuters)
OpenAI removes a 2026 IPO catalyst. Sam Altman ruled out a flotation this year in a Friday interview published Saturday, saying safety work made listing ill-advised. His answer favoured delaying the transaction without committing to a 2027 date. Keeping the company private postpones a potentially trillion-dollar public-market test; investors in its listed compute suppliers face continued uncertainty over financing and deployment plans. (Reuters)
Nvidia weighs another major customer investment. Reuters reported after Friday’s US close that Nvidia (NVDA US) was considering up to US$10bn as an anchor in Anthropic’s IPO, which could raise US$100bn at around US$2tn valuation. Discussions remain conditional. The potential funding would deepen supplier-customer ties while increasing exposure to the financing needs of frontier-model developers; Friday’s share close preceded this report. (Reuters) Nvidia (NVDA US) is our Core Recommendation.
Americas
Server makers outperform their cloud customer. At Friday’s US close, Dell Technologies (DELL US) rose 11.98% to US$567.29, HPE (HPE US) gained 12.44% to US$62.09 and HP (HPQ US) added 8.40%. Reuters linked the gains to Oracle’s (ORCL US) earlier earnings beat; Oracle fell 1.74%. The divergence favours equipment demand over cloud profitability, but preceded the weekend safety-pacing debate. (Reuters)
ACV takeover narrows the remaining upside. ACV Auctions (ACVA US) jumped 44.18% to US$10.41 at Friday’s US close, reacting to Copart’s (CPRT US) previously announced US$10.50 cash offer. The approximately US$1.9bn equity deal broadens Copart into dealer-to-dealer wholesale auctions. With the shares nine US cents below consideration, investors now depend principally on completion rather than operating upside; closing conditions still apply. (Copart / Reuters)
Local production could alter Chinese automakers’ access. Trump said in a Friday interview he would accept Chinese manufacturers building cars in the US and hiring Americans, while opposing imports routed through Mexico. Existing restrictions still effectively prohibit Chinese passenger-vehicle sales or production, alongside electric-vehicle tariffs exceeding 100%. The remarks create policy optionality for local investment, but do not constitute a regulatory change. (Reuters)
Kroger protects profit as sales guidance weakens. Kroger (KR US) cut FY26 identical-sales growth excluding fuel to 0.2–0.8% from 1–2%, while retaining adjusted EPS guidance of US$5.10–5.30. Second-quarter adjusted EPS of US$1.09 beat US$1.06 consensus. Shares gained 2.70% to US$58.49 at Friday’s US close. Cost discipline and higher-margin operations support earnings, but the reduced sales target reinforces pressure on grocery spending. (Kroger / Reuters)
Chevron ring-fences Venezuela expansion funding. CEO Mike Wirth said Friday that Chevron (CVX US) would finance its planned US$7bn Venezuelan expansion entirely from cash generated by three existing local ventures. Previously agreed expansion terms target roughly 600,000 barrels daily by 2031. Funding internally limits fresh parent cash exposure, but execution remains sensitive to operating conditions and the ventures’ ability to generate sufficient cash. (Reuters)
Roblox widens distribution beyond its own app. Roblox (RBLX US) said Friday that creators would be able to offer standalone games across mobile, PC and consoles, while browser access and offline modes broaden distribution. Its Build tool has already produced about 9,000 games, with 71% of creators new to Roblox Studio. Lower production and access barriers could expand engagement, but monetisation remains unquantified. (Reuters)
Salesforce extends agents into persistent workflows. Salesforce (CRM US) introduced job-specific Agentforce agents Friday and a runtime supporting work across days and weeks. It reports seven billion Agentic Work Units across Agentforce and Slack over two years, including 3.2bn in its second quarter. The figures measure activity, rather than revenue; converting that usage into profitable subscriptions remains the central investment test. (Salesforce)
Boeing advances a deal with key engineers. A tentative agreement reached Friday covers roughly 17,000 SPEEA professional and technical employees, offering an initial 10% wage increase followed by annual 4% guaranteed raises. Ratification remains outstanding. The deal could reduce disruption risk for Boeing (BA US), whose engineers are essential to delayed 737 MAX 10 and 777-9 certification, while adding labour costs. (SPEEA / Reuters)
Greater China
China ties futures licences more closely to capital. Rules published by the CSRC on Friday separate basic brokerage and advisory activities from trading businesses. From 1 January 2027, registered-capital requirements range from RMB100m for domestic brokerage to RMB500m for one trading business and RMB1bn for two or more. Tighter ownership, governance and subsidiary controls favour adequately capitalised operators as firms assess expansion and compliance costs. (CSRC / CSRC rules)
Ginko China attracts a lower takeover valuation. CVC Capital Partners entered final talks to buy EQT’s mainland contact-lens business on Friday, Reuters reported. The potential US$700–800m valuation includes debt, below EQT’s earlier target of at least US$1bn. Financial terms remain unsettled and talks could fail. The indicative pricing highlights the gap between sellers’ expectations and buyers’ willingness to fund Chinese consumer assets. (Reuters)
Chow Tai Fook seeks RMB10bn of mainland financing. The jeweller (1929.HK) disclosed on Friday evening that it had applied to register panda bonds of up to RMB10bn, for issuance in multiple tranches when appropriate. Proceeds would support working capital, product development, store upgrades and market expansion, alongside repayment of existing borrowings. The proposed programme diversifies funding and maturities; registration and issuance are not completed financing. (Securities Times)
Foton proposes a RMB1.5bn related-party asset sale. The vehicle maker (600166.SH) disclosed plans on Friday to transfer 378 Miyun factory assets to BAIC New Energy’s Beijing branch for RMB1.5163bn including VAT. The package covers land, buildings and equipment. Shareholder approval remains outstanding. Monetising these assets should reduce depreciation and release capital, but the proposed disposal gain depends on completion and final accounting. (Company / Yicai)
Asia ex. China
Micron’s Taiwan rewards leave strike risk unresolved. Micron (MU US) announced Friday rewards equivalent to 35–68 months’ pay for fiscal 2026, with minimum cash compensation of T$1.7m. The Taoyuan union nevertheless said no agreement had been reached and sought bonuses linked to 15% of operating profit. With about 15,000 Taiwan staff, a stoppage remains a material supply risk despite the unusually large payouts. (Reuters)
BRICS diplomacy keeps Iran and the UAE talking. Both states backed Saturday’s declaration urging restraint in the six-month Middle East war and protection of trade, energy flows and maritime security. Their leaders held the highest-level bilateral meeting since the conflict began. The communiqué offers a channel for de-escalation, but announced no settlement; shipping and energy exposure still depends on subsequent actions rather than summit language. (Reuters)
Maybank takes full ownership of its Etiqa holding company. Maybank (1155 MK) completed the purchase of Ageas’s 30.95% stake on Friday for cash consideration equivalent to €1.1bn, including a €53m pre-completion dividend. The transaction values Maybank Ageas Holdings at €3.5bn, roughly twice 2025 IFRS equity. Full control gives Maybank greater scope to integrate banking, wealth and insurance offerings across its Malaysian and Singapore customer bases. (Company / New Straits Times)
CICT settles acquisition and management fees in units. CapitaLand Integrated Commercial Trust (C38U SP) issued 19.6m units on Friday, including 16.5m at S$2.3607 each to settle the S$39m Paragon acquisition fee. Another 3.0m units paid half the April–June base management fee. Total units increased to 7.974bn. Paying fees in units preserves cash while modestly enlarging the denominator over which future distributions are shared. (Tiger Brokers)
EMEA and Others
European bank chiefs seek an urgent capital moratorium. Santander chair Ana Botín and ten other banking leaders urged EU institutions to pause capital increases and propose regulatory simplification legislation in early 2027, according to Cinco Días. They also sought fewer barriers to cross-border scale. The request frames capital relief as support for lending and investment; it remains industry lobbying rather than an adopted change. (Cinco Días)
BASF prices a further reduction in Harbour Energy. BASF (BAS GR) sold about 133m Harbour Energy (HBR LN) shares on Friday at 266p, raising approximately £353.8m. Institutions took 80m shares and Harbour purchased 53m. Completion will reduce BASF’s voting stake from about 24.3% to 16.4%. The disposal releases cash for BASF, while Harbour’s participation absorbs part of the placement and limits immediate market supply. (Dow Jones)
Berkeley preserves profit guidance while conserving cash. Berkeley (BKG LN) maintained its four-year £1.4bn pre-tax profit plan in Friday’s trading update, but warned buyers could defer purchases until after October’s Budget and election uncertainty. It repurchased £60m of shares in May–August and expects around £250m half-year net cash. Paused land investment protects financial flexibility, although weaker transaction activity remains the principal earnings constraint. (Company)
Sweden’s election points to a one-seat opposition majority. The election authority projected 175 seats for Magdalena Andersson’s centre-left bloc against 174 for the governing right in the 349-seat parliament, Reuters reported early Monday SGT. The estimate used results from 4,853 of 6,312 districts. Such a narrow provisional margin leaves government formation and fiscal direction uncertain, making final counting and coalition negotiations the next material catalysts. (Reuters)
Traders’ corner
Our Technical View
Weekly Chart: Price executed a breakdown last week, penetrating both its consolidation range and previous low support pivot via a decisive bearish candle. Technical momentum reinforces this breakdown, as the RSI has turned bearish and accelerates lower beneath its neutral 50-midline. As long as counter-trend rallies remain capped below this converted resistance zone, we could expect a sustained downward drift toward the next support target.
Daily Chart: The emergence of a falling window directly through the previous low support pivot marks a transition from consolidation into a high-velocity volatility expansion phase to the downside. The steep downward slope of the RSI below neutral parameters accelerate trend slope decay. Provided lower-timeframe price action preserves lower-high structural integrity and respects the converted supply boundary on brief retracements, technical probabilities heavily favours a sustained downside impulse wave toward prospective lower support zones.
Our Technical View
Weekly Chart: Price sustained its dominant downward trajectory, driving price directly into proximity with its overhead support zone. The persistent sell-side pressure reflects an intact downward structural framework. A high-conviction violation and close beneath this critical demand floor would convert the historic support anchor into a fresh supply ceiling. Technical probabilities suggest that a confirmed breach will unleash downside acceleration and clear the path of least resistance toward lower extension targets.
Daily Chart: Price has extended its downward trajectory, bringing the market into direct confluence with its previous low support zone. The technical posture exhibits early signs of seller deceleration as the RSI approaches oversold territory and begins to curve upward. However, structural integrity remains binary: a high-conviction violation and daily close beneath this historical pivot would complete a structural polarity flip, converting the support floor into a supply ceiling and confirming a deeper trend continuation wave toward lower expansion targets.
Disclosures and disclaimers
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


