
分析员
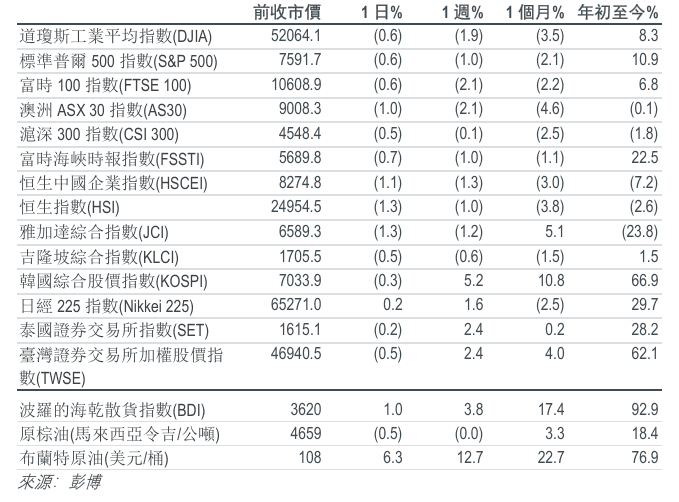
主要指数
头条新闻
行业更新 | 中国汽车
中国乘用车批发出货量的按年跌幅由7月份的按年0.2%扩大至8月份的按年5.7%,但按月销量增长仍维持在4.7%的正水平。当局重申了60天的付款期限政策。 9月的新车发布日程比成都车展更加紧密。维持「与大市一致」评级。首选「买入」股份:比亚迪、吉利、宁德时代及敏实。首选「沽出」股份:理想汽车。
公司业绩 | 新鸿基地产 (16 HK/买入/港币116.7元/目标价:HK$143.80)
新鸿基地产2026财政年度基础溢利按年增长4.6%至港币228.5亿元,大致符合市场预期。 融资成本下降以及出售帝景园所获收益,抵销了营业利润3.6%的跌幅。 香港物业发展利润率由2026财政年度上半年的7.6%提升至2026财政年度下半年的14.8%。 每股派息增长4.3%至港币3.91元,而净资产负债率则降至10.7%。 管理层将2027财政年度香港合约销售目标定为港币330亿元。 我们预期物业及租赁市场的复苏将对2027财政年度的盈利构成支持。 维持「买入」评级;目标价:港币143.8元。
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


