
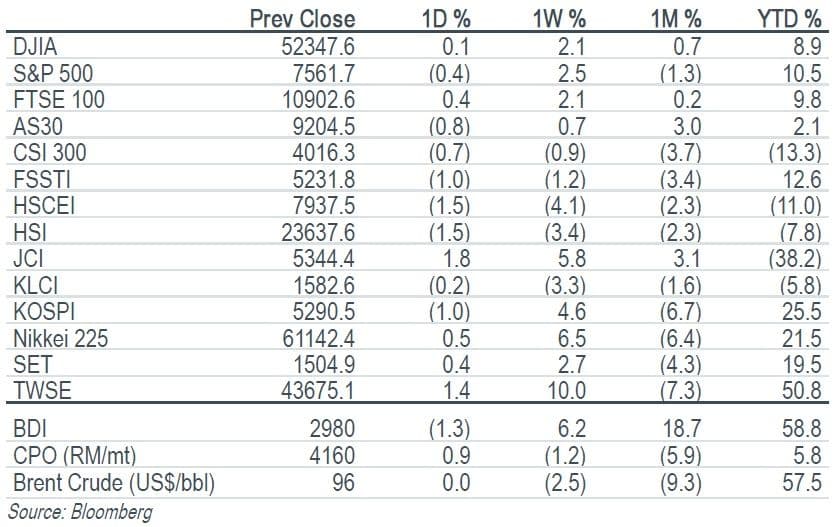
Key Indices
Top Stories
Company Results | Bangkok Expressway and Metro (BEM TB/BUY/Bt6.30/Target: Bt8.50)
- BEM’s 3Q26 net profit reached a record high of Bt1.1b, +5% yoy, in line with our and consensus estimates. Expressway traffic and MRT ridership began to recover in the second half of Oct 26, and our forecast for 7% yoy earnings growth in 4Q26 remains achievable. The share price has declined, while fundamentals remain unchanged. Maintain BUY with a target price of Bt8.50.
Company Results | Ratch Group (RATCH TB/BUY/Bt36.50/Target: Bt44.00)
- RATCH reported a strong 3Q26 earnings recovery, with normalised profit rising 13% yoy and 74% qoq to Bt2.30b, driven by improved HKP availability and dispatch. We expect earnings to remain resilient in 4Q26, supported by stable contributions from major power plants. Looking ahead, PDP 2026 and potential value creation from the RG site through PPA extensions and data centre development offer additional upside. Maintain BUY with a target price of Bt44.00.
Company Results | Stecon Group (STECON TB/BUY/Bt18.40/Target: Bt26.50)
- STECON reported 3Q26 net profit of Bt387m (+137% yoy, -58% qoq), beating our and consensus expectations. Revenue reached a record Bt11.5b (+53% yoy, +22% qoq), while gross margin improved to 7.52%. STECON also expanded its DC investment scope to include operating and under-construction projects in Thailand and overseas. We maintain BUY with a higher target price of Bt26.50.
Company Update | Central Plaza Hotel (CENTEL TB/BUY/Bt45.00/Target: Bt58.00)
- CENTEL should report 3Q26 net profit of Bt220m (+37.1% yoy, +32.1% qoq), driven by a strong hotel performance in the Maldives and upcountry destinations, alongside improving food margins. Refinancing and new bond issuance should generate further interest savings from 4Q26. Strong forward bookings support positive 4Q26 RevPar growth across key markets. Food performance remains resilient despite headwinds, and seasonal demand should strengthen. Maintain BUY with a target price of Bt58.00, supported by strong bookings, lower financing costs, and margin improvement.
What’s Inside
Company Results | AP (Thailand) (AP TB/BUY/Bt8.05/Target: Bt9.25)
- AP posted a 3Q26 net profit of Bt1,207m (+4.6% yoy, +13.5% qoq), beating estimates on lower SG&A and higher other income, despite softer gross profit margin (29.85%). Per the analyst meeting, 4Q26 momentum is driven by 17 new launches (raised to Bt59b) and full-quarter JV contribution, with 85% of 2026 presales secured. Maintain BUY, with a target price of Bt9.25, favouring AP for its strong competitive position, resilient operating performance, and an attractive 6.5% dividend yield.
Company Results | Star Petroleum Refining (SPRC TB/BUY/Bt13.4/Target: Bt17)
- SPRC reported 3Q26 net profit of Bt10.2b (+547% yoy, +48% qoq), broadly in line with expectations, while core profit declined 47% qoq to Bt3.8b. Market GRM fell to US$14.3/bbl, pressured by higher crude costs and diesel price intervention. We expect resilient middle-distillate cracks to support refining margins in 1H27, although policy measures remain a near-term earnings headwind. Our conservative forecasts leave room for upside from potential policy easing. Maintain BUY with a target price of Bt17.00, implying 27% upside.
Company Update | CP ALL (CPALL TB/BUY/Bt47.00/Target: Bt63.00)
- Management guided for qtd SSSG to maintain its positive momentum from 3Q26 (3Q26: +2.5% yoy), supported by a low base in 4Q25 which was impacted by the Half-half plus copayment scheme and flooding. Moreover, the more favourable weather conditions would support foot traffic to stores. Earnings momentum is expected to improve from 4Q26 onward. Maintain BUY with a target price of Bt63.00, based on 2027F PE of 17x.
Company Update | Praram 9 Hospital (PR9 TB/BUY/Bt18.60/Target: Bt24.60)
- The tone from the analyst meeting was positive. PR9’s performance rebounded in Oct 26, supported by improving foreign patient arrivals. Management expects 4Q26 to deliver another set of record-high earnings, driven by Middle Eastern and Myanmar patients, pent-up demand and cost control. Foreign referral partnerships, including Qatar Ministry of Health, Garuda Airline and International SOS, should support growth from 1Q27. ICU expansion and advanced medical technology will enhance capacity and complex care services. Maintain BUY; target price: Bt24.60.
Company Update | PTT Oil and Retail (OR TB/HOLD/Bt12.60/Target: Bt12.50)
- Management expects the impact of government measures on OR to be relatively limited. Sales volumes are entering the high season in 4Q26, with volumes expected to increase both qoq and yoy. However, the normalisation of marketing margins is likely to result in lower net profit qoq in 4Q26. We believe uncertainty surrounding the review of OR’s investment plan in Cambodia will remain an overhang on its share price. Maintain HOLD. Target price: Bt12.50.
Company Update | WHA Corporation (WHA TB/BUY/Bt4.96/Target: Bt6.10)
- The tone of WHA’s 3Q26 analyst meeting was slightly positive. Management maintained its 2026 land sales target and expects transfers to accelerate in 4Q26. Looking ahead, we expect data centre investment momentum to strengthen in 2027, alongside growing demand from high-tech industries. We expect data centre demand to remain a key earnings driver in 2027, supported by renewed customer discussions and potential expansion of ESIE5. Maintain BUY with a target price of Bt6.10.
Top Stories
Company Results | Bangkok Expressway and Metro (BEM TB/BUY/Bt6.30/Target: Bt8.50)
- BEM’s 3Q26 net profit reached a record high of Bt1.1b, +5% yoy, in line with our and consensus estimates. Expressway traffic and MRT ridership began to recover in the second half of Oct 26, and our forecast for 7% yoy earnings growth in 4Q26 remains achievable. The share price has declined, while fundamentals remain unchanged. Maintain BUY with a target price of Bt8.50.
Company Results | Ratch Group (RATCH TB/BUY/Bt36.50/Target: Bt44.00)
- RATCH reported a strong 3Q26 earnings recovery, with normalised profit rising 13% yoy and 74% qoq to Bt2.30b, driven by improved HKP availability and dispatch. We expect earnings to remain resilient in 4Q26, supported by stable contributions from major power plants. Looking ahead, PDP 2026 and potential value creation from the RG site through PPA extensions and data centre development offer additional upside. Maintain BUY with a target price of Bt44.00.
Company Results | Stecon Group (STECON TB/BUY/Bt18.40/Target: Bt26.50)
- STECON reported 3Q26 net profit of Bt387m (+137% yoy, -58% qoq), beating our and consensus expectations. Revenue reached a record Bt11.5b (+53% yoy, +22% qoq), while gross margin improved to 7.52%. STECON also expanded its DC investment scope to include operating and under-construction projects in Thailand and overseas. We maintain BUY with a higher target price of Bt26.50.
Company Update | Central Plaza Hotel (CENTEL TB/BUY/Bt45.00/Target: Bt58.00)
- CENTEL should report 3Q26 net profit of Bt220m (+37.1% yoy, +32.1% qoq), driven by a strong hotel performance in the Maldives and upcountry destinations, alongside improving food margins. Refinancing and new bond issuance should generate further interest savings from 4Q26. Strong forward bookings support positive 4Q26 RevPar growth across key markets. Food performance remains resilient despite headwinds, and seasonal demand should strengthen. Maintain BUY with a target price of Bt58.00, supported by strong bookings, lower financing costs, and margin improvement.
What’s Inside
Company Results | AP (Thailand) (AP TB/BUY/Bt8.05/Target: Bt9.25)
- AP posted a 3Q26 net profit of Bt1,207m (+4.6% yoy, +13.5% qoq), beating estimates on lower SG&A and higher other income, despite softer gross profit margin (29.85%). Per the analyst meeting, 4Q26 momentum is driven by 17 new launches (raised to Bt59b) and full-quarter JV contribution, with 85% of 2026 presales secured. Maintain BUY, with a target price of Bt9.25, favouring AP for its strong competitive position, resilient operating performance, and an attractive 6.5% dividend yield.
Company Results | Star Petroleum Refining (SPRC TB/BUY/Bt13.4/Target: Bt17)
- SPRC reported 3Q26 net profit of Bt10.2b (+547% yoy, +48% qoq), broadly in line with expectations, while core profit declined 47% qoq to Bt3.8b. Market GRM fell to US$14.3/bbl, pressured by higher crude costs and diesel price intervention. We expect resilient middle-distillate cracks to support refining margins in 1H27, although policy measures remain a near-term earnings headwind. Our conservative forecasts leave room for upside from potential policy easing. Maintain BUY with a target price of Bt17.00, implying 27% upside.
Company Update | CP ALL (CPALL TB/BUY/Bt47.00/Target: Bt63.00)
- Management guided for qtd SSSG to maintain its positive momentum from 3Q26 (3Q26: +2.5% yoy), supported by a low base in 4Q25 which was impacted by the Half-half plus copayment scheme and flooding. Moreover, the more favourable weather conditions would support foot traffic to stores. Earnings momentum is expected to improve from 4Q26 onward. Maintain BUY with a target price of Bt63.00, based on 2027F PE of 17x.
Company Update | Praram 9 Hospital (PR9 TB/BUY/Bt18.60/Target: Bt24.60)
- The tone from the analyst meeting was positive. PR9’s performance rebounded in Oct 26, supported by improving foreign patient arrivals. Management expects 4Q26 to deliver another set of record-high earnings, driven by Middle Eastern and Myanmar patients, pent-up demand and cost control. Foreign referral partnerships, including Qatar Ministry of Health, Garuda Airline and International SOS, should support growth from 1Q27. ICU expansion and advanced medical technology will enhance capacity and complex care services. Maintain BUY; target price: Bt24.60.
Company Update | PTT Oil and Retail (OR TB/HOLD/Bt12.60/Target: Bt12.50)
- Management expects the impact of government measures on OR to be relatively limited. Sales volumes are entering the high season in 4Q26, with volumes expected to increase both qoq and yoy. However, the normalisation of marketing margins is likely to result in lower net profit qoq in 4Q26. We believe uncertainty surrounding the review of OR’s investment plan in Cambodia will remain an overhang on its share price. Maintain HOLD. Target price: Bt12.50.
Company Update | WHA Corporation (WHA TB/BUY/Bt4.96/Target: Bt6.10)
- The tone of WHA’s 3Q26 analyst meeting was slightly positive. Management maintained its 2026 land sales target and expects transfers to accelerate in 4Q26. Looking ahead, we expect data centre investment momentum to strengthen in 2027, alongside growing demand from high-tech industries. We expect data centre demand to remain a key earnings driver in 2027, supported by renewed customer discussions and potential expansion of ESIE5. Maintain BUY with a target price of Bt6.10.
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


