
Country Daily
CSPC Pharmaceutical Group / Tencent Holdings
Analyst
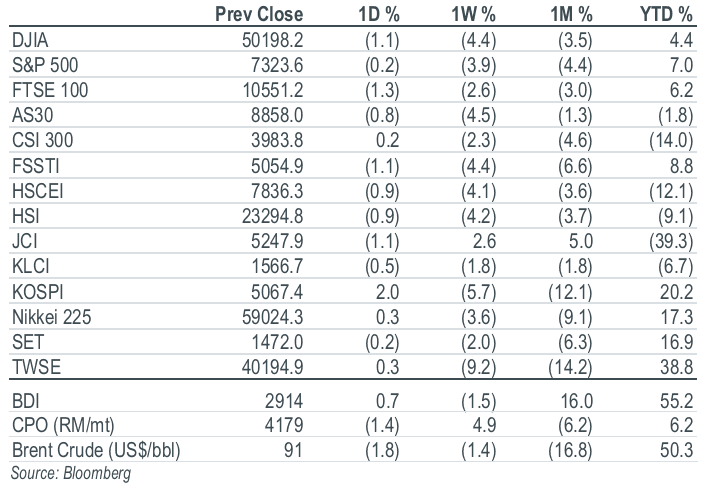
Key Indices
Top Stories
Company Results | CSPC Pharmaceutical Group (1093 HK/BUY/HK$7.99/Target: HK$10.00)
CSPC’s 9M26 results beat expectations, with revenue up 27.0% yoy to Rmb25.3b and underlying net profit surging 134.5% yoy to Rmb7.2b. In 3Q26, product sales grew 10.1% yoy, offsetting a 19.9% yoy fall in licence fee income. CSPC targets positive revenue growth in 2027, supported by continued innovative product launches and globalisation efforts. We foresee limited revenue growth visibility given the unpredictable timing of licensing income. Maintain BUY with a lower target price of HK$10.00 on limited 2027 growth visibility.
Company Results | Tencent Holdings (700 HK/BUY/HK$372.80/Target: HK$500.00)
Tencent’s 3Q26 results came in slightly below expectations. Revenue rose 7.5% yoy to Rmb207.3b, 1.6% below both our estimate and consensus. Higher AI-related costs weighed on profitability, with gross profit missing both estimates and non-IFRS operating profit coming in 6.8% below our estimate. Non-IFRS net profit fell 5.7% yoy to Rmb66.5b, broadly in line with expectations. Higher capex and compute prepayments widened the free cash outflow, with Tencent shifting to net debt. Maintain BUY with a lower target price of HK$500.00.
Top Stories
Company Results | CSPC Pharmaceutical Group (1093 HK/BUY/HK$7.99/Target: HK$10.00)
CSPC’s 9M26 results beat expectations, with revenue up 27.0% yoy to Rmb25.3b and underlying net profit surging 134.5% yoy to Rmb7.2b. In 3Q26, product sales grew 10.1% yoy, offsetting a 19.9% yoy fall in licence fee income. CSPC targets positive revenue growth in 2027, supported by continued innovative product launches and globalisation efforts. We foresee limited revenue growth visibility given the unpredictable timing of licensing income. Maintain BUY with a lower target price of HK$10.00 on limited 2027 growth visibility.
Company Results | Tencent Holdings (700 HK/BUY/HK$372.80/Target: HK$500.00)
Tencent’s 3Q26 results came in slightly below expectations. Revenue rose 7.5% yoy to Rmb207.3b, 1.6% below both our estimate and consensus. Higher AI-related costs weighed on profitability, with gross profit missing both estimates and non-IFRS operating profit coming in 6.8% below our estimate. Non-IFRS net profit fell 5.7% yoy to Rmb66.5b, broadly in line with expectations. Higher capex and compute prepayments widened the free cash outflow, with Tencent shifting to net debt. Maintain BUY with a lower target price of HK$500.00.
Analyst
Key Indices
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

Our latest research

20 Nov 2026
China Automobile Weekly / Alibaba Group / Kuaishou / Lenovo Group / NetEase / PDD Holdings / China Resources Mixc Lifestyle

18 Nov 2026
JD / Miniso / Tencent Music Entertainment Group / Sino Land

17 Nov 2026