
Company Coverage
ASL Marine (ASL SP): FY26: Strong Earnings Growth And Improving Outlook
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.30
S$0.41
+36.7%
S$0.43
Analyst
Analyst
Highlights
- FY26 revenue and earnings are in line, forming 95% and 103% of our forecasts respectively.
- Ship chartering drove growth, with revenue up 10% yoy and gross margin improving to 20.1%, while ship repair remained resilient.
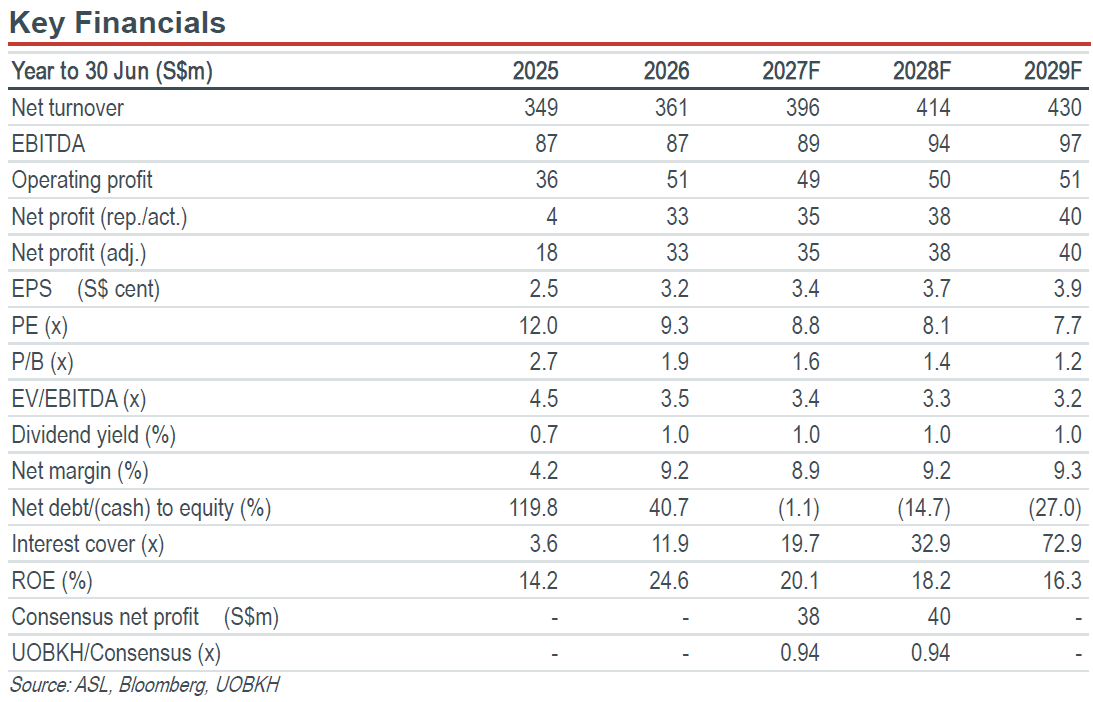
- Maintain BUY with a slightly lower target price of S$0.41, pegged to an unchanged 12x FY27F PE.
Analysis
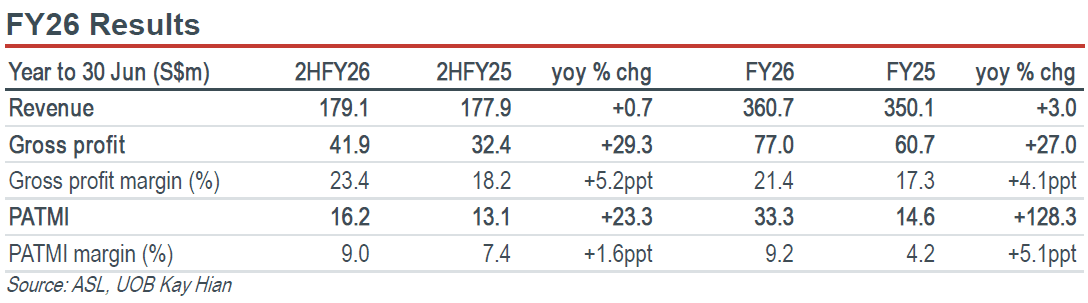
- Earnings slightly ahead of expectations. ASL Marine (ASL) reported FY26 revenue of S$360.7m (+3.0% yoy) and PATMI of S$33.3m (+128.3% yoy), accounting for 95% and 103% of our respective forecasts. Growth was driven by stronger ship chartering contributions while shipbuilding and ship repair remained stable. The earnings beat was supported by stronger ship chartering contributions and continued deleveraging, with finance costs falling 66% yoy. Gross margins improved 4.1ppt to 21.4%, while PATMI margin improved 5.1ppt to 9.2%.
- 2HFY26 margins strengthened on better business mix. For 2HFY26, ASL reported revenue of S$179.1m (+0.7% yoy) and PATMI of S$16.2m (+23.3% yoy). Ship chartering revenue rose 18.6% yoy, offsetting softer ship repair and shipbuilding contributions. Gross margin expanded 5.2ppt yoy to 23.4%, driven by stronger ship chartering margins on higher charter rates, lower maintenance and operating costs, alongside improved shipbuilding margins.
Highlights
- FY26 revenue and earnings are in line, forming 95% and 103% of our forecasts respectively.
- Ship chartering drove growth, with revenue up 10% yoy and gross margin improving to 20.1%, while ship repair remained resilient.
- Maintain BUY with a slightly lower target price of S$0.41, pegged to an unchanged 12x FY27F PE.
Analysis
- Earnings slightly ahead of expectations. ASL Marine (ASL) reported FY26 revenue of S$360.7m (+3.0% yoy) and PATMI of S$33.3m (+128.3% yoy), accounting for 95% and 103% of our respective forecasts. Growth was driven by stronger ship chartering contributions while shipbuilding and ship repair remained stable. The earnings beat was supported by stronger ship chartering contributions and continued deleveraging, with finance costs falling 66% yoy. Gross margins improved 4.1ppt to 21.4%, while PATMI margin improved 5.1ppt to 9.2%.
- 2HFY26 margins strengthened on better business mix. For 2HFY26, ASL reported revenue of S$179.1m (+0.7% yoy) and PATMI of S$16.2m (+23.3% yoy). Ship chartering revenue rose 18.6% yoy, offsetting softer ship repair and shipbuilding contributions. Gross margin expanded 5.2ppt yoy to 23.4%, driven by stronger ship chartering margins on higher charter rates, lower maintenance and operating costs, alongside improved shipbuilding margins.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
S$0.30
S$0.41
+36.7%
S$0.43
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at the following link: this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
