
Company Coverage
KE Holdings Inc (2423 HK): 3Q26: Strong Earnings Beat On Margin Expansion And Lower Opex
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$45.60
HK$65.00
42.5%
HK$60.00
Analyst
Highlights
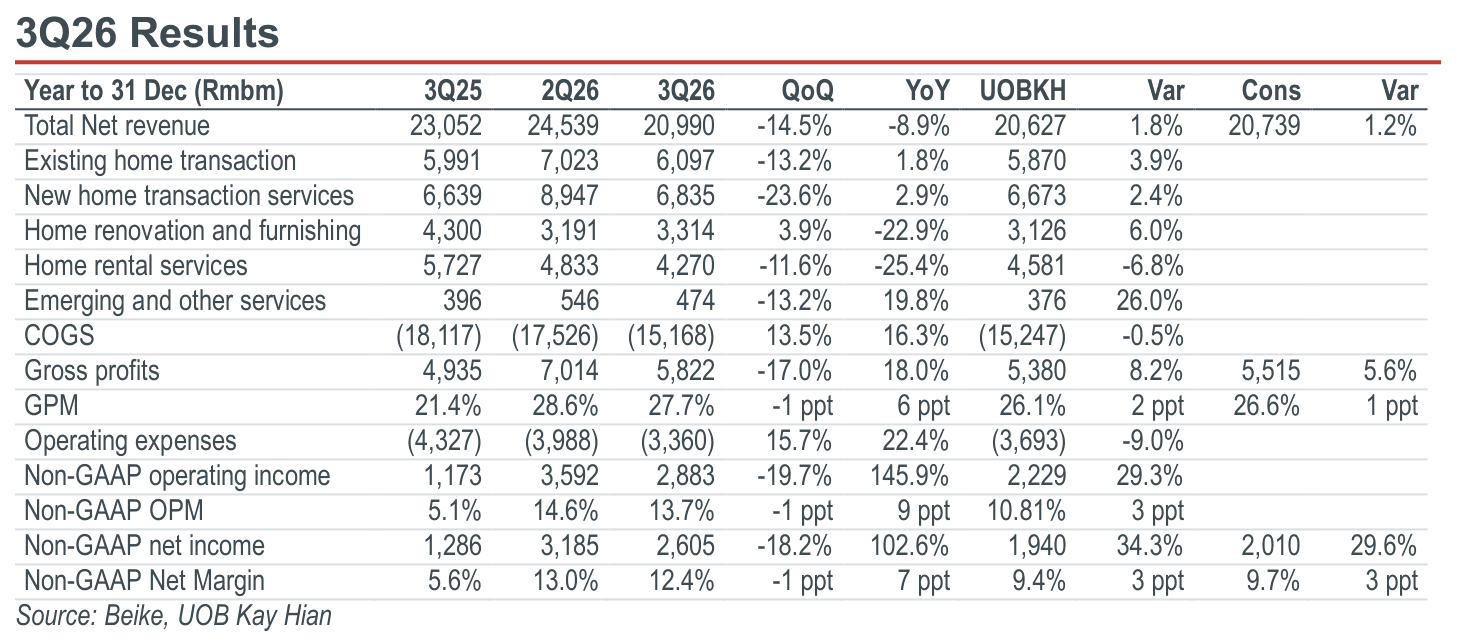
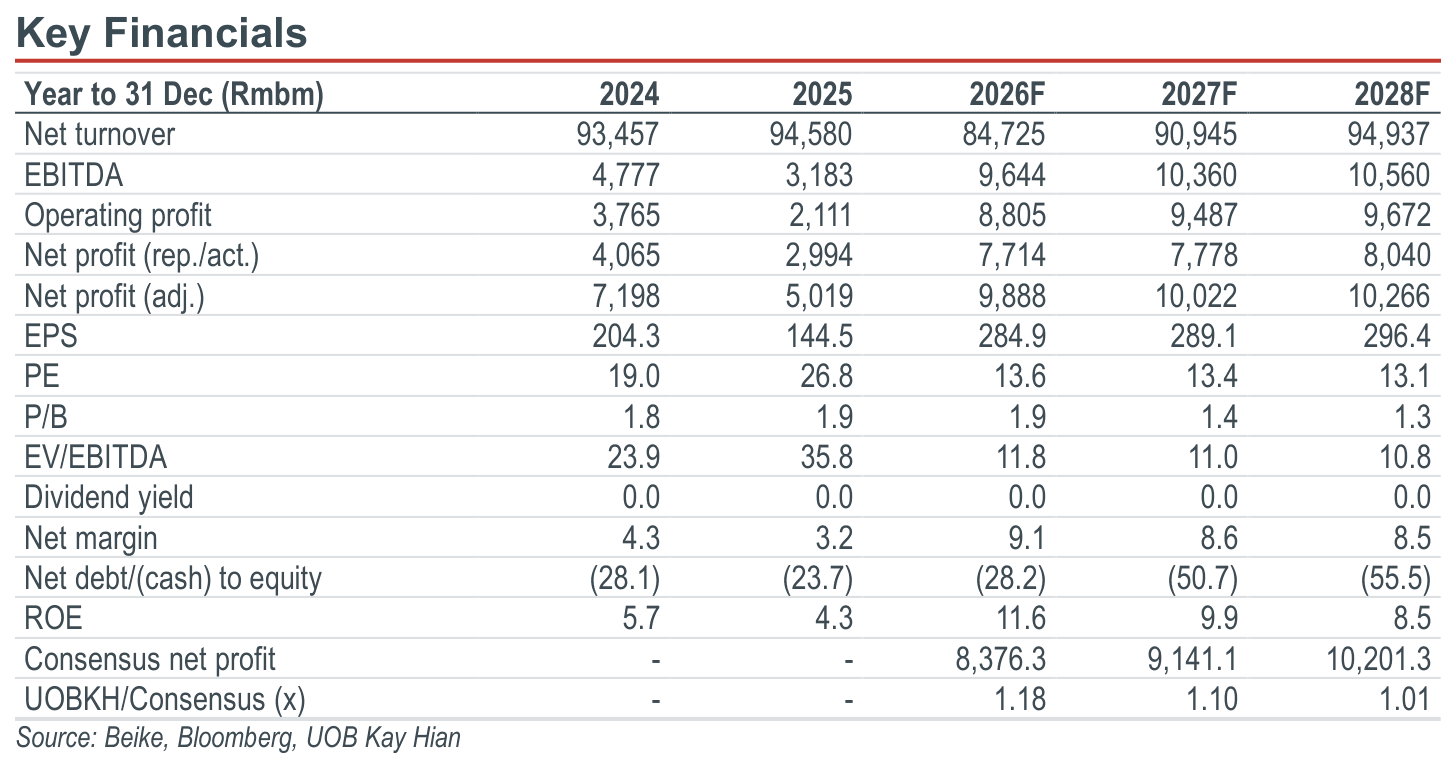
- Beike’s 3Q26 operating profit beat expectations. Revenue declined 8.9% yoy to Rmb21.0b, in line with our estimate, while total GTV rose 4.5% yoy. Non-GAAP operating profit rose 145.9% yoy to Rmb2.9b, 29.3% above our estimate, as operating margin expanded 8.6ppt yoy to 13.7%. Management guided for 4Q26 revenue of around Rmb20b (down 9-10% yoy) and an operating margin of around 10%, implying operating profit of approximately Rmb2.0b. Maintain BUY with a higher target price of HK$65.00 (US$25.00).
Analysis
- Revenue declined, but underlying transaction businesses remained resilient. KE Holdings' (Beike) 3Q26 revenue declined 8.9% yoy to Rmb21.0b (2Q26: -5.7% yoy), while total GTV increased 4.5% yoy. Revenue from existing-home transaction services grew 1.8% yoy (2Q26: +4.5% yoy) to Rmb6.1b, as existing-home GTV grew 3.0% yoy to Rmb520.9b. Commission revenue fell 4.6% yoy to Rmb4.6b on a 7.3% yoy decline in Lianjia-served GTV, while platform, franchise and other value-added service revenue rose 27.2% yoy to Rmb1.5b on a 9.3% yoy rise in GTV served by connected agents. Revenue from new-home transaction services rose 2.9% yoy to Rmb6.8b on 5.3% yoy GTV growth to Rmb206.8b, with Lianjia-served new home GTV up 11.2% yoy.
- New initiatives. Home renovation and furnishing revenue fell 22.9% yoy to Rmb3.3b, 6.0% above our estimate, which the company attributed to the deferred revenue impact of lower GTV in prior periods as it optimised its customer acquisition channel mix. Home rental services revenue fell 25.4% yoy to Rmb4.3b, 6.8% below our estimate, as a rising share of the Carefree Rent business shifts to net service fee recognition, partly offset by growth in rental units. Emerging and other services revenue rose 19.8% yoy to Rmb474m, driven by financial services.
Highlights
- Beike’s 3Q26 operating profit beat expectations. Revenue declined 8.9% yoy to Rmb21.0b, in line with our estimate, while total GTV rose 4.5% yoy. Non-GAAP operating profit rose 145.9% yoy to Rmb2.9b, 29.3% above our estimate, as operating margin expanded 8.6ppt yoy to 13.7%. Management guided for 4Q26 revenue of around Rmb20b (down 9-10% yoy) and an operating margin of around 10%, implying operating profit of approximately Rmb2.0b. Maintain BUY with a higher target price of HK$65.00 (US$25.00).
Analysis
- Revenue declined, but underlying transaction businesses remained resilient. KE Holdings' (Beike) 3Q26 revenue declined 8.9% yoy to Rmb21.0b (2Q26: -5.7% yoy), while total GTV increased 4.5% yoy. Revenue from existing-home transaction services grew 1.8% yoy (2Q26: +4.5% yoy) to Rmb6.1b, as existing-home GTV grew 3.0% yoy to Rmb520.9b. Commission revenue fell 4.6% yoy to Rmb4.6b on a 7.3% yoy decline in Lianjia-served GTV, while platform, franchise and other value-added service revenue rose 27.2% yoy to Rmb1.5b on a 9.3% yoy rise in GTV served by connected agents. Revenue from new-home transaction services rose 2.9% yoy to Rmb6.8b on 5.3% yoy GTV growth to Rmb206.8b, with Lianjia-served new home GTV up 11.2% yoy.
- New initiatives. Home renovation and furnishing revenue fell 22.9% yoy to Rmb3.3b, 6.0% above our estimate, which the company attributed to the deferred revenue impact of lower GTV in prior periods as it optimised its customer acquisition channel mix. Home rental services revenue fell 25.4% yoy to Rmb4.3b, 6.8% below our estimate, as a rising share of the Carefree Rent business shifts to net service fee recognition, partly offset by growth in rental units. Emerging and other services revenue rose 19.8% yoy to Rmb474m, driven by financial services.
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$45.60
HK$65.00
42.5%
HK$60.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Nov 2026
Baidu Inc (9888 HK): 3Q26: Earnings Beat; AI Cloud Growth Cushions Ad Weakness

6 Nov 2026
ECARX Holdings Inc (ECX US) - 3Q26: Memory Costs Cut Gross Margin To 7.0%

27 Oct 2026
ZTE Corporation (763 HK): 3Q26: Operating Profit Dragged Down By Weak Margins And High Operating Expenses
Our latest research

17 Nov 2026
New World Development (17 HK): Rights Issue Strenghtens Balance Sheet but Dilutes NAV per Share by 90%
17 Nov 2026
TA: Trip.com Group (9961 HK) / ANTA Sports (2020 HK)
17 Nov 2026