Company Coverage
iFlytek Inc (002230 CH): 3Q26: Revenue Below Expectations; Elevated R&D Spending Weighs On Profitability
SELL (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
Rmb36.12
Rmb30.00
-16.9%
Rmb39.00
Analyst
Highlights
- iFlytek’s 3Q26 revenue missed expectations, rising 8.0% yoy to Rmb6.56b amid its ongoing business refocus. Gross margin eased 0.4ppt yoy to 40.0%. Attributable net profit rose 31.0% yoy to Rmb226m, supported by non-recurring investment gains and government grants, while net loss excluding non-recurring items reached Rmb126m as elevated R&D and selling expenses weighed on profitability. Further Spark upgrades are scheduled for 22 October.
- Downgrade to SELL with a lower target price of Rmb30.00.
Analysis
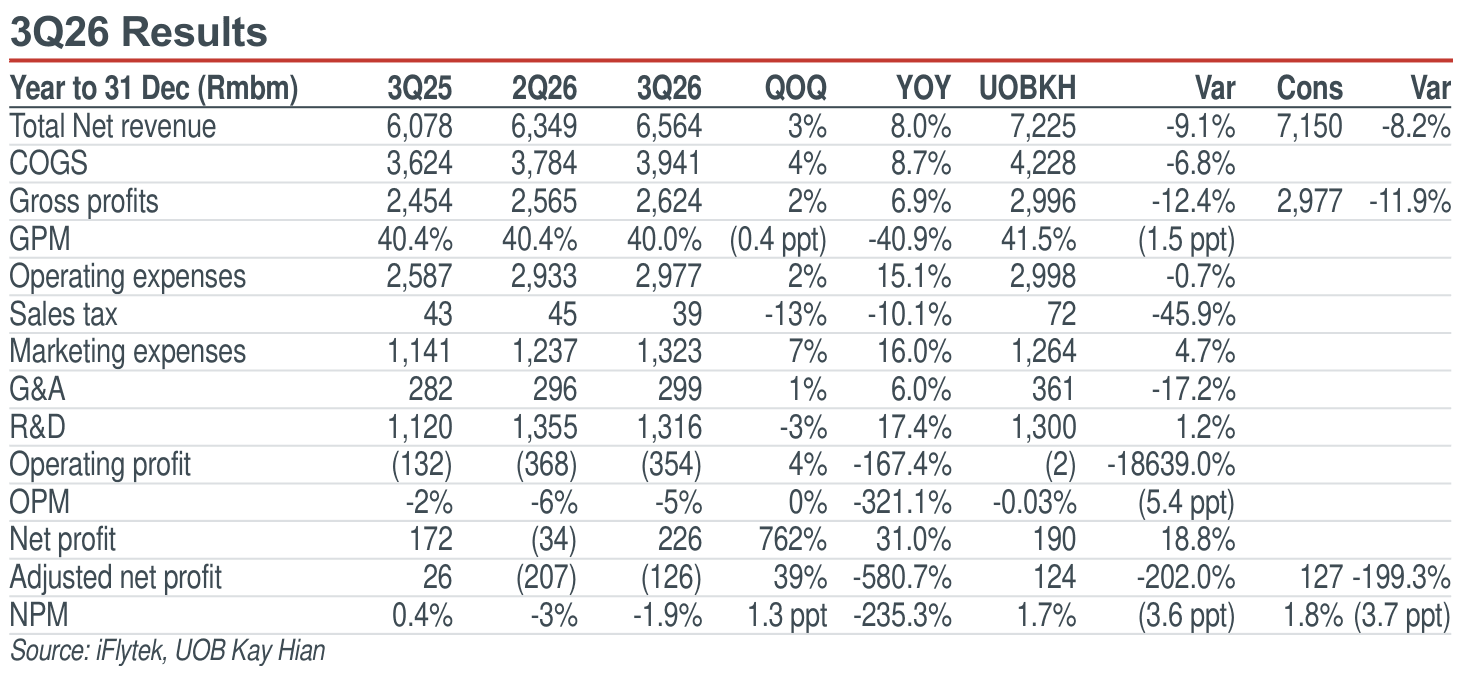
- Revenue growth picked up in 3Q26 but fell short of our forecast. iFlytek Inc’s (iFlytek) revenue rose 8.0% yoy to Rmb6.56b, 8-9% below our forecast of Rmb7.23b, bringing 9M26 revenue to Rmb18.19b, up 7.1% yoy. Management is taking a more selective approach to government projects, scaling back the smart city business while focusing on smart education and smart medical services. G-end revenue declined 2.4% yoy as the smart city business contracted, while smart education and smart medical revenue each grew more than 20% yoy. Meanwhile, the company continues to strengthen its consumer offerings and deepen enterprise penetration.
- Higher operating expenses weighed on profitability. 3Q26 gross margin eased 0.4ppt yoy to 40.0%, while operating expenses expanded 15.1% yoy to Rmb2.98b. R&D and selling expenses increased 17.4% and 16.0% yoy, respectively, to Rmb1.32b each, widening the operating loss to Rmb354m. Attributable net profit rose 31.0% yoy to Rmb226m, supported by Rmb352m of non-recurring gains, including Rmb248m in investment gains and Rmb165m in government grants. Excluding non-recurring items, iFlytek swung to a net loss of Rmb126m from a net profit in 3Q25.
Highlights
- iFlytek’s 3Q26 revenue missed expectations, rising 8.0% yoy to Rmb6.56b amid its ongoing business refocus. Gross margin eased 0.4ppt yoy to 40.0%. Attributable net profit rose 31.0% yoy to Rmb226m, supported by non-recurring investment gains and government grants, while net loss excluding non-recurring items reached Rmb126m as elevated R&D and selling expenses weighed on profitability. Further Spark upgrades are scheduled for 22 October.
- Downgrade to SELL with a lower target price of Rmb30.00.
Analysis
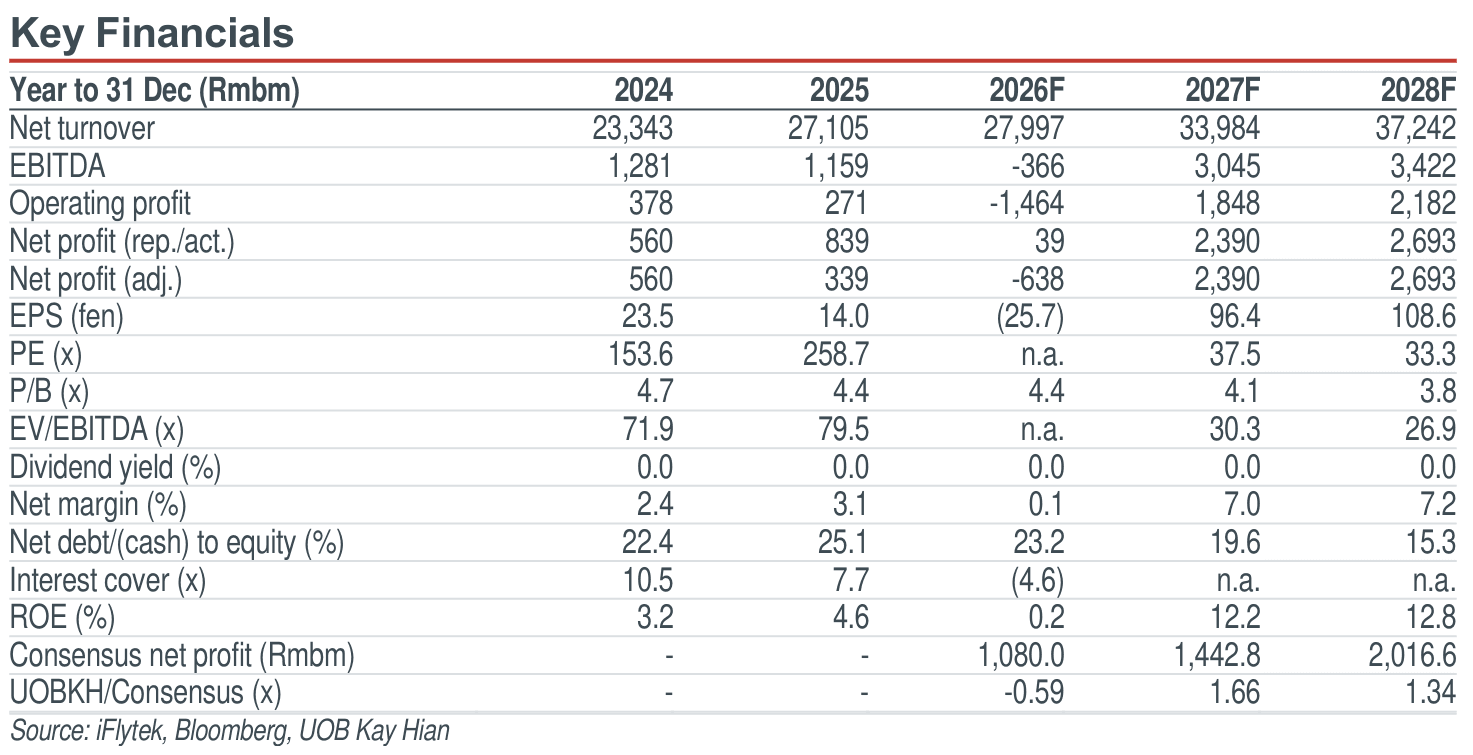
- Revenue growth picked up in 3Q26 but fell short of our forecast. iFlytek Inc’s (iFlytek) revenue rose 8.0% yoy to Rmb6.56b, 8-9% below our forecast of Rmb7.23b, bringing 9M26 revenue to Rmb18.19b, up 7.1% yoy. Management is taking a more selective approach to government projects, scaling back the smart city business while focusing on smart education and smart medical services. G-end revenue declined 2.4% yoy as the smart city business contracted, while smart education and smart medical revenue each grew more than 20% yoy. Meanwhile, the company continues to strengthen its consumer offerings and deepen enterprise penetration.
- Higher operating expenses weighed on profitability. 3Q26 gross margin eased 0.4ppt yoy to 40.0%, while operating expenses expanded 15.1% yoy to Rmb2.98b. R&D and selling expenses increased 17.4% and 16.0% yoy, respectively, to Rmb1.32b each, widening the operating loss to Rmb354m. Attributable net profit rose 31.0% yoy to Rmb226m, supported by Rmb352m of non-recurring gains, including Rmb248m in investment gains and Rmb165m in government grants. Excluding non-recurring items, iFlytek swung to a net loss of Rmb126m from a net profit in 3Q25.
SELL (Downgraded)
Current price:
Target price:
Upside:
Previous TP :
Rmb36.12
Rmb30.00
-16.9%
Rmb39.00
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

2 Oct 2026
New World Development (17 HK): FY26: Core Profit Turns Positive; 11 SKIES Exit Helps Long-term Cash Flow, But Debt Metrics Warrant Caution

21 Sept 2026
Alibaba Health Information Technology (241 HK): 1HFY27 Preview: Lowers FY27 Revenue Growth Target To 7-10% yoy On Subsidy Optimisation; Earnings Guidance Unchanged
Our latest research
21 Oct 2026
TA: CK Asset (1113 HK) / Nongfu Spring (9633 HK)

21 Oct 2026
Alibaba Group (9988 HK): 2QFY27 Preview: Cloud Growth Accelerates; Losses Continue To Narrow

21 Oct 2026