
Company Coverage
Haidilao International Holding (6862 HK): 1H26: Operating Profit Beats But Net Profit Misses; Dividend A Surprise; Main Brand Steady Expansion And Sub-Brand Enters Replication Stage
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$12.25
HK$16.70
+36.3%
HK$18.30
Analyst
Analyst
Highlights
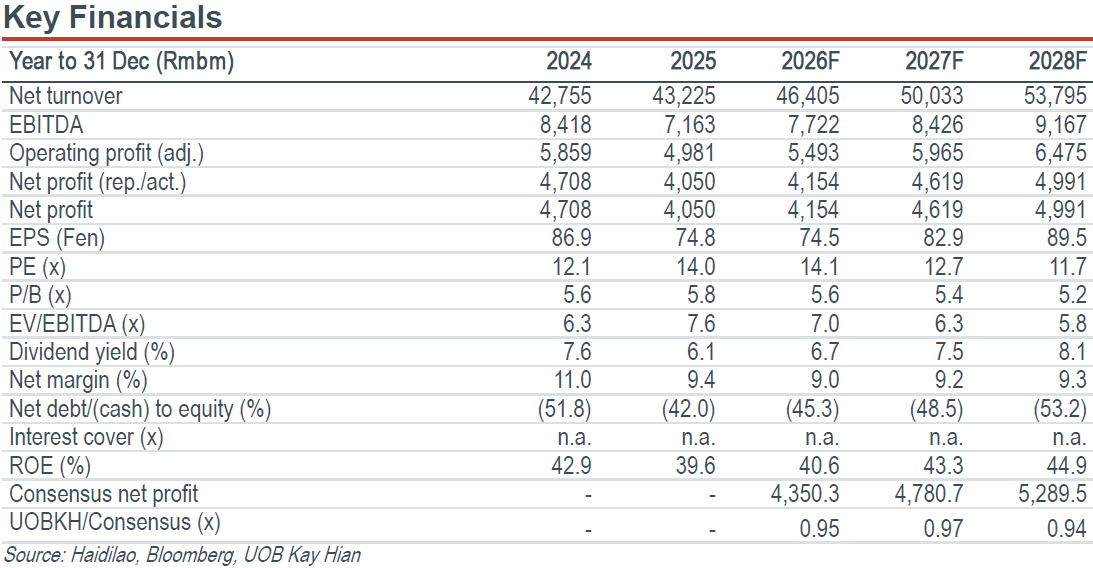
- Haidilao’s 1H26 operating profit beat, driven by expense savings but net profit missed consensus due to non-operating items. The company raising the dividend payout to 100% was a surprise.
Looking ahead, the Haidilao brand will maintain a steady store opening pace at mid-single-digit growth this year, while new brands, food stall hot pot and sushi, will enter the replication stage. The delivery business is expected to sustain rapid growth at a high double-digit rate in 2H26, but its profitability is lower than that of dine-in. Maintain BUY, cut target price by 9% to HK$16.70.
Analysis
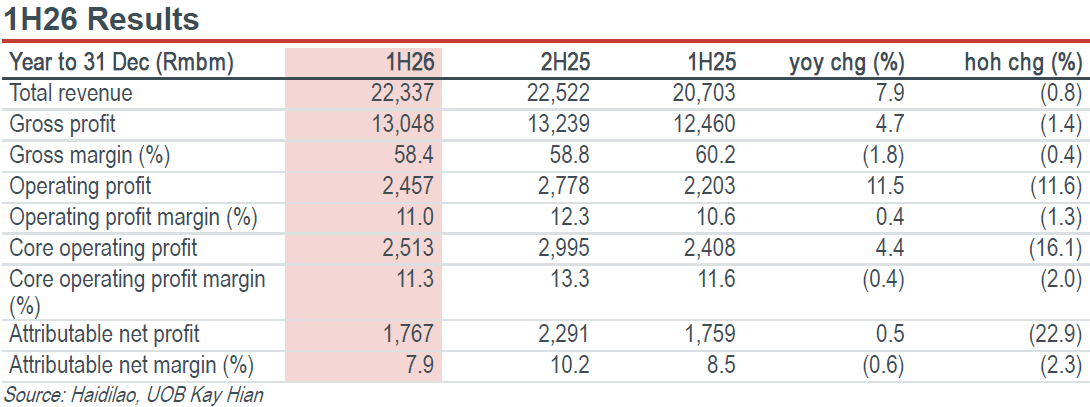
- 1H26 operating profit beat but net profit missed due to non-operating items; raised dividend payout to 100% a surprise. Haidilao International Holding (Haidilao) reported its 1H26 results. In 1H26, revenue was Rmb22,337m (+8% yoy, -1% hoh), missing VA consensus by 1%. Gross profit was Rmb13,048m (+5% yoy, -1% hoh), with a gross margin of 58.4% (-1.8ppt yoy, -0.4ppt hoh), primarily due to: a) higher revenue contribution from businesses with lower gross margin, and b) impact of various consumer promotional concessions aimed at enhancing customer experience. Operating profit was Rmb2,457m (+12% yoy, -12% hoh), 5% above VA consensus, with an operating margin of 11.0% (+0.4 ppt yoy, -1.3ppt hoh). The yoy improvement in operating margin was driven by: a) lower labour costs (-2.0ppt yoy); and b) reduced depreciation and amortisation expenses (-1.5ppt yoy), which more than offset gross margin contraction and rising other expenses, primarily from increased charges by delivery platforms (+1.5ppt yoy). Core operating profit was Rmb2,513m (+4% yoy, -16% hoh), with a core operating margin of 11.3% (-0.4ppt yoy, -2.0 ppt hoh). Net profit was Rmb1,767m (+0.5% yoy, -23% hoh), missing VA consensus by 3%, with a net margin of 7.9% (-0.6ppt yoy, -2.3 ppt hoh).
Highlights
- Haidilao’s 1H26 operating profit beat, driven by expense savings but net profit missed consensus due to non-operating items. The company raising the dividend payout to 100% was a surprise.
Looking ahead, the Haidilao brand will maintain a steady store opening pace at mid-single-digit growth this year, while new brands, food stall hot pot and sushi, will enter the replication stage. The delivery business is expected to sustain rapid growth at a high double-digit rate in 2H26, but its profitability is lower than that of dine-in. Maintain BUY, cut target price by 9% to HK$16.70.
Analysis
- 1H26 operating profit beat but net profit missed due to non-operating items; raised dividend payout to 100% a surprise. Haidilao International Holding (Haidilao) reported its 1H26 results. In 1H26, revenue was Rmb22,337m (+8% yoy, -1% hoh), missing VA consensus by 1%. Gross profit was Rmb13,048m (+5% yoy, -1% hoh), with a gross margin of 58.4% (-1.8ppt yoy, -0.4ppt hoh), primarily due to: a) higher revenue contribution from businesses with lower gross margin, and b) impact of various consumer promotional concessions aimed at enhancing customer experience. Operating profit was Rmb2,457m (+12% yoy, -12% hoh), 5% above VA consensus, with an operating margin of 11.0% (+0.4 ppt yoy, -1.3ppt hoh). The yoy improvement in operating margin was driven by: a) lower labour costs (-2.0ppt yoy); and b) reduced depreciation and amortisation expenses (-1.5ppt yoy), which more than offset gross margin contraction and rising other expenses, primarily from increased charges by delivery platforms (+1.5ppt yoy). Core operating profit was Rmb2,513m (+4% yoy, -16% hoh), with a core operating margin of 11.3% (-0.4ppt yoy, -2.0 ppt hoh). Net profit was Rmb1,767m (+0.5% yoy, -23% hoh), missing VA consensus by 3%, with a net margin of 7.9% (-0.6ppt yoy, -2.3 ppt hoh).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$12.25
HK$16.70
+36.3%
HK$18.30
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

26 Aug 2026
Xtep International Holdings (1368 HK): 1H26: Revenue Misses But Gross Margin Expansion Drives Better-Than-Expected Net Profit; Lowers Full-Year Revenue Target

31 Aug 2026
Miniso (MNSO US/9896 HK): 1H26: Revenue Slightly Exceeds Guidance But Profit Misses; Expect Operating Profit To Decline By A High Single Digit In 2026

28 Aug 2026
Inner Mongolia Yili Industrial Group (600887 CH): 2Q26: Revenue Misses But Operating Margin Expansion Better Than Expected; Reiterates Mid-Single-Digit Revenue Growth Target
Our latest research
11 Sept 2026
TA: Meituan (3690 HK) / MiniMax (0100 HK)

11 Sept 2026
Sun Hung Kai Properties (16 HK): FY26: DPS Up 4.3% yoy And Net Gearing Down To 10.7%; Further Market Recovery To Support Earnings In FY27
10 Sept 2026