
Company Coverage
Galaxy Entertainment Group (27 HK): 3Q26: Market Share Gains; Normalised EBITDA Down 9% qoq On Margin Pressure
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$34.84
HK$43.00
+23.4%
HK$47.00
Analyst
Analyst
Highlights
Galaxy’s 3Q26 GGR market share increased 1.7ppt qoq to 22.0%, but normalised EBITDA declined 9% qoq on a deterioration in margin.
Galaxy’s market share during the Golden Week was largely flat yoy, affected by unfavourable luck in the premium segment. Looking ahead, management remains cautiously optimistic on 4Q26, expecting consumer confidence to improve towards year-end.
Phase 4 remains on schedule for completion by end-27, adding around 1,350 suites with no additional gaming tables currently allocated. At StarWorld, the renovation-related EBITDA drag is expected to be at similar level of HK$20m in 4Q26, before the completion in 1Q27.
Maintain BUY; cut target price by 9% to HK$43.00.
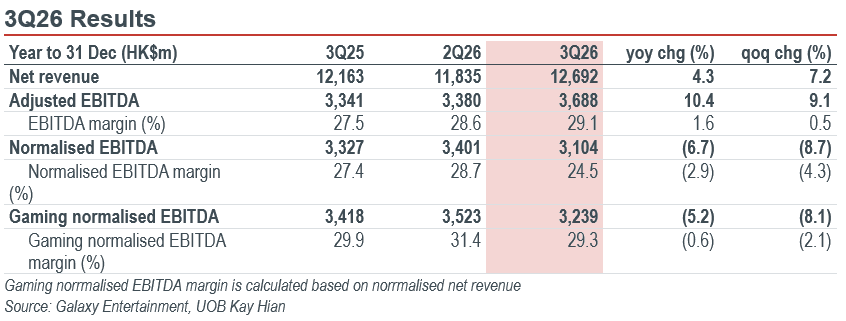
Analysis
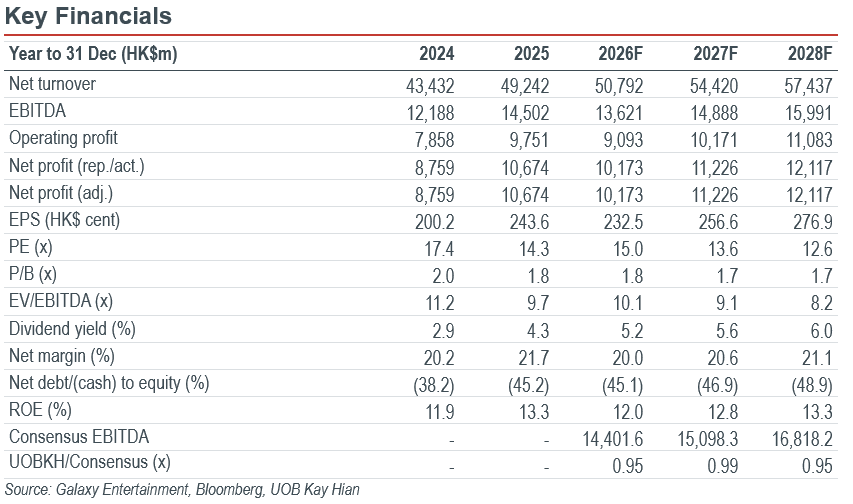
3Q26 GGR market share increased 1.7ppt qoq to 22.0%; normalised EBITDA declined 9% qoq on margin deterioration. In 3Q26, Galaxy Entertainment Group (Galaxy) achieved net revenue of HK$12,692m (+4% yoy, +7% qoq). Adjusted EBITDA was HK$3,688m (+10% yoy, +9% qoq). Galaxy played lucky in 3Q26, which increased its adjusted EBITDA by HK$584m. Thus, normalised adjusted EBITDA came in at HK$3,104m (-7% yoy, -9% qoq), and normalised EBITDA margin was 24.5% (-2.9ppt yoy, -4.3ppt qoq). For the gaming & entertainment division, normalised adjusted property EBITDA was HK$3,239m (-5% yoy, -8% qoq), with normalised EBITDA margin at 29.3% (-0.6ppt yoy, -2.1ppt qoq).
Highlights
Galaxy’s 3Q26 GGR market share increased 1.7ppt qoq to 22.0%, but normalised EBITDA declined 9% qoq on a deterioration in margin.
Galaxy’s market share during the Golden Week was largely flat yoy, affected by unfavourable luck in the premium segment. Looking ahead, management remains cautiously optimistic on 4Q26, expecting consumer confidence to improve towards year-end.
Phase 4 remains on schedule for completion by end-27, adding around 1,350 suites with no additional gaming tables currently allocated. At StarWorld, the renovation-related EBITDA drag is expected to be at similar level of HK$20m in 4Q26, before the completion in 1Q27.
Maintain BUY; cut target price by 9% to HK$43.00.
Analysis
3Q26 GGR market share increased 1.7ppt qoq to 22.0%; normalised EBITDA declined 9% qoq on margin deterioration. In 3Q26, Galaxy Entertainment Group (Galaxy) achieved net revenue of HK$12,692m (+4% yoy, +7% qoq). Adjusted EBITDA was HK$3,688m (+10% yoy, +9% qoq). Galaxy played lucky in 3Q26, which increased its adjusted EBITDA by HK$584m. Thus, normalised adjusted EBITDA came in at HK$3,104m (-7% yoy, -9% qoq), and normalised EBITDA margin was 24.5% (-2.9ppt yoy, -4.3ppt qoq). For the gaming & entertainment division, normalised adjusted property EBITDA was HK$3,239m (-5% yoy, -8% qoq), with normalised EBITDA margin at 29.3% (-0.6ppt yoy, -2.1ppt qoq).
BUY (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$34.84
HK$43.00
+23.4%
HK$47.00
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.


