
Company Coverage
BYD Electronics (285 HK): 2Q26: Yet Another Huge Miss On Weaker Margins
SELL (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$24.76
HK$14.50
-41.4%
HK$19.90
Analyst
Analyst
Highlights
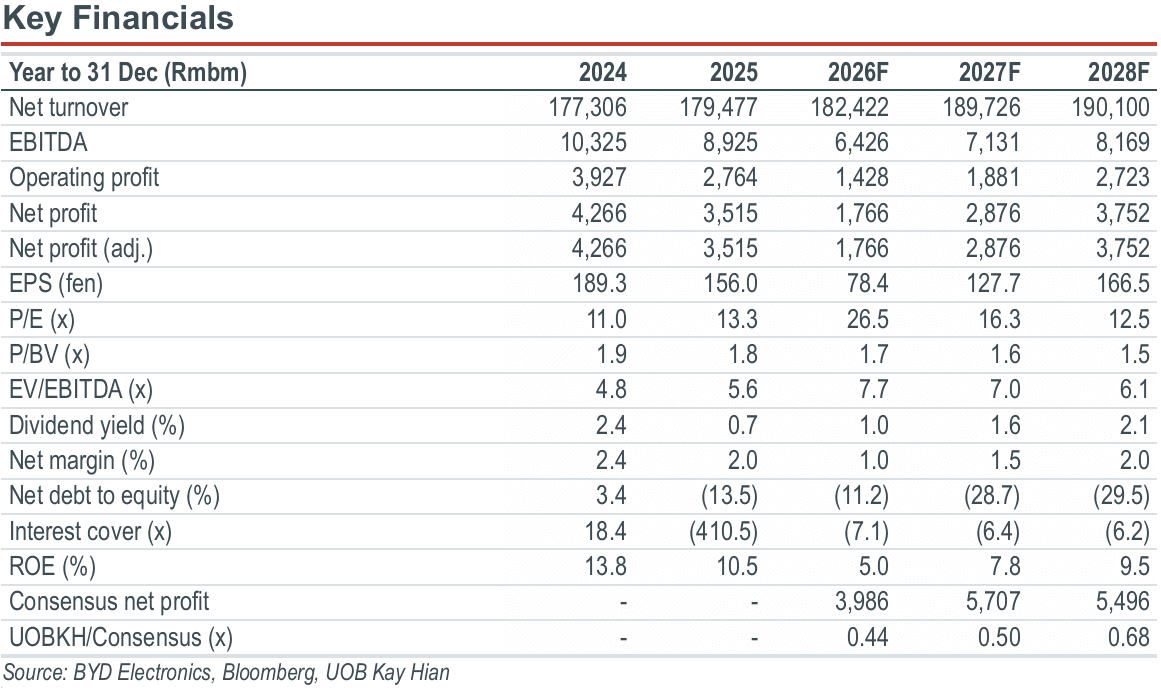
BYDE’s 2Q26 results were another big miss, declining 64.0% yoy to Rmb399m and missing consensus estimates by 46.4% due to forex losses and much worse than expected margins.
AI server seems to be the key growth driver for BYDE in the future, but we believe that it will not be able to offset core business’ weaknesses until 2028.
Maintain SELL. Cut target price to HK$14.50.
Analysis
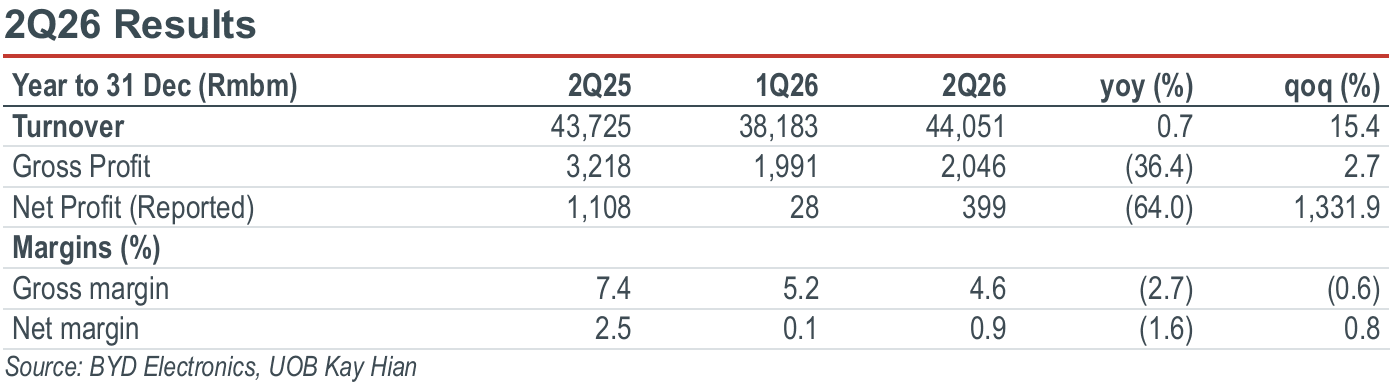
2Q26 is another huge miss. BYD Electronics’ (BYDE) 2Q26 revenue rose 0.7% yoy and 15.4% qoq to Rmb44.1b, 6.3% ahead of consensus’ estimates of Rmb41.4b. However, gross margin sharply deteriorated by 2.7ppt yoy and 0.6ppt qoq to 4.6%, a 0.9ppt miss vs consensus estimates due to ongoing margin pressure and deteriorating mix. Coupled with an unfavourable exchange rate leading to an around Rmb700m forex loss for 1H26, net profit plunged 64.0% yoy to Rmb399m, which is 46.4% below consensus estimates.
1H26 segment performance: New energy vehicle revenue rose 6.4% yoy to Rmb13.6b (16.6% of group’s revenue), which is largely in line; Smart terminal grew 1.3% yoy to Rmb67.9b (82.5% of group’s revenue), primarily driven by a better-than-expected assembly business which grew 5.1% yoy to Rmb56.0b, likely attributable to higher memory prices; but the component business deteriorated 13.4% yoy to Rmb11.9b as expected, and this had led to a deterioration in profitability as the assembly business has a much lower, single-digit % margin. AI computing infrastructure – the segment carrying the entire structural story – shrank 10.2% yoy to just Rmb753m, or 0.9% of group revenue.
Highlights
BYDE’s 2Q26 results were another big miss, declining 64.0% yoy to Rmb399m and missing consensus estimates by 46.4% due to forex losses and much worse than expected margins.
AI server seems to be the key growth driver for BYDE in the future, but we believe that it will not be able to offset core business’ weaknesses until 2028.
Maintain SELL. Cut target price to HK$14.50.
Analysis
2Q26 is another huge miss. BYD Electronics’ (BYDE) 2Q26 revenue rose 0.7% yoy and 15.4% qoq to Rmb44.1b, 6.3% ahead of consensus’ estimates of Rmb41.4b. However, gross margin sharply deteriorated by 2.7ppt yoy and 0.6ppt qoq to 4.6%, a 0.9ppt miss vs consensus estimates due to ongoing margin pressure and deteriorating mix. Coupled with an unfavourable exchange rate leading to an around Rmb700m forex loss for 1H26, net profit plunged 64.0% yoy to Rmb399m, which is 46.4% below consensus estimates.
1H26 segment performance: New energy vehicle revenue rose 6.4% yoy to Rmb13.6b (16.6% of group’s revenue), which is largely in line; Smart terminal grew 1.3% yoy to Rmb67.9b (82.5% of group’s revenue), primarily driven by a better-than-expected assembly business which grew 5.1% yoy to Rmb56.0b, likely attributable to higher memory prices; but the component business deteriorated 13.4% yoy to Rmb11.9b as expected, and this had led to a deterioration in profitability as the assembly business has a much lower, single-digit % margin. AI computing infrastructure – the segment carrying the entire structural story – shrank 10.2% yoy to just Rmb753m, or 0.9% of group revenue.
SELL (Maintained)
Current price:
Target price:
Upside:
Previous TP :
HK$24.76
HK$14.50
-41.4%
HK$19.90
Analyst
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

27 Aug 2026
Ningbo Joyson Electronic Corporation (600699 CH): 2Q26: Results Miss On Top-Line, Revenue To Resume Growth In 2H26

1 Sept 2026
Z.AI Co (2513 HK): 1H26: Revenue Miss And Mix-Driven Margin Pressure, But ARR Momentum Remains Robust

31 Aug 2026
Meituan (3690 HK): 2Q26: Earnings Beat; Food Delivery Remains Profitable Amid 3Q26 Seasonal Pressure
Our latest research
11 Sept 2026
TA: Meituan (3690 HK) / MiniMax (0100 HK)

11 Sept 2026
Sun Hung Kai Properties (16 HK): FY26: DPS Up 4.3% yoy And Net Gearing Down To 10.7%; Further Market Recovery To Support Earnings In FY27
10 Sept 2026