
Company Coverage
JD.com (9618 HK) - 3Q26 Results Preview: Broadly In Line; Food Delivery Losses Narrow As International Expansion Continues
BUY (Maintained)
Current price:
Target price:
Upside:
HK$104.90
HK$148.00
+41.1%
Analyst
Highlights
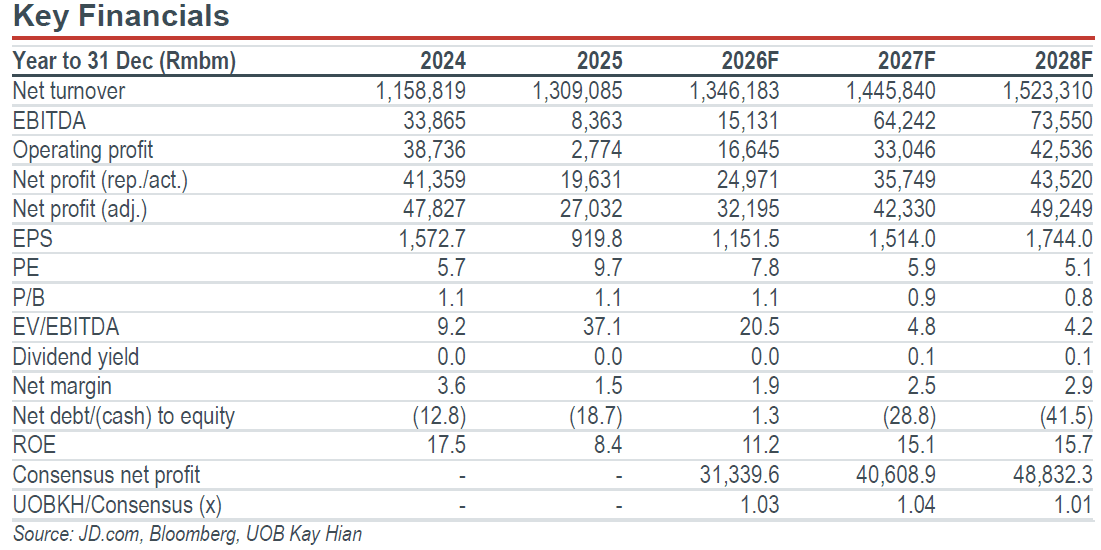
- JD.com is expected to report its 3Q26 results in mid-November. We forecast group revenue to grow 3.5% yoy to Rmb309.6b, broadly in line with consensus, supported by JD Retail’s return to positive growth. Retail operating margin should remain broadly stable yoy, while narrowing food delivery and Jingxi losses should support group earnings recovery, partly offset by a modest increase in international losses as JD continues its European expansion.
- Maintain BUY with an unchanged target price of HK$148.00 (US$38.00).
Analysis
- Group revenue broadly in line with expectations; retail revenue returns to positive growth. We forecast JD.com (JD) 3Q26 group revenue growing 3.5% yoy to Rmb309.6b, broadly in line with market expectations of 4%, supported by JD Retail’s return to positive revenue growth of 3% yoy to Rmb258.1b. Group revenue growth should outpace JD Retail’s by around 0.5ppt, with the narrower gap reflecting a smaller contribution from food delivery fulfilment revenue to group growth. By product category, electronics and home appliances revenue is expected to decline 4% yoy to Rmb123.8b, vs a 12% decline in 2Q26, driven by healthy smartphone growth and narrowing declines in home appliances and computers. Meanwhile, general merchandise revenue is expected to grow 8% yoy to Rmb105.3b, supported by supermarket growth approaching double digits and a recovery in fashion and home categories, although fashion continues to weigh on overall growth. On profitability, JD Retail’s gross margin is expected to reach a record high, supported by a higher general merchandise mix and faster growth in commission and advertising revenue. However, higher AI-related R&D and fulfilment expenses should partly offset these gains, leaving retail operating margin broadly stable yoy.
- New business losses continue to narrow, alongside growing food delivery orders. New business losses are expected to narrow from around Rmb10b in 2Q26 to around Rmb9b in 3Q26, supported by a better-than-expected qoq loss reduction in food delivery. Food delivery order volume continues to grow qoq despite lower total investment, reflecting improving unit economics, while losses should decline by more than half yoy. Management indicated that Jingxi losses should also narrow to below Rmb2b in 3Q26, from above Rmb2b in 2Q26, following peak investment in the previous quarter. These improvements should partly offset a modest qoq increase in international business losses, which are expected to remain below Rmb2b as JD.com’s European expansion continues.
Highlights
- JD.com is expected to report its 3Q26 results in mid-November. We forecast group revenue to grow 3.5% yoy to Rmb309.6b, broadly in line with consensus, supported by JD Retail’s return to positive growth. Retail operating margin should remain broadly stable yoy, while narrowing food delivery and Jingxi losses should support group earnings recovery, partly offset by a modest increase in international losses as JD continues its European expansion.
- Maintain BUY with an unchanged target price of HK$148.00 (US$38.00).
Analysis
- Group revenue broadly in line with expectations; retail revenue returns to positive growth. We forecast JD.com (JD) 3Q26 group revenue growing 3.5% yoy to Rmb309.6b, broadly in line with market expectations of 4%, supported by JD Retail’s return to positive revenue growth of 3% yoy to Rmb258.1b. Group revenue growth should outpace JD Retail’s by around 0.5ppt, with the narrower gap reflecting a smaller contribution from food delivery fulfilment revenue to group growth. By product category, electronics and home appliances revenue is expected to decline 4% yoy to Rmb123.8b, vs a 12% decline in 2Q26, driven by healthy smartphone growth and narrowing declines in home appliances and computers. Meanwhile, general merchandise revenue is expected to grow 8% yoy to Rmb105.3b, supported by supermarket growth approaching double digits and a recovery in fashion and home categories, although fashion continues to weigh on overall growth. On profitability, JD Retail’s gross margin is expected to reach a record high, supported by a higher general merchandise mix and faster growth in commission and advertising revenue. However, higher AI-related R&D and fulfilment expenses should partly offset these gains, leaving retail operating margin broadly stable yoy.
- New business losses continue to narrow, alongside growing food delivery orders. New business losses are expected to narrow from around Rmb10b in 2Q26 to around Rmb9b in 3Q26, supported by a better-than-expected qoq loss reduction in food delivery. Food delivery order volume continues to grow qoq despite lower total investment, reflecting improving unit economics, while losses should decline by more than half yoy. Management indicated that Jingxi losses should also narrow to below Rmb2b in 3Q26, from above Rmb2b in 2Q26, following peak investment in the previous quarter. These improvements should partly offset a modest qoq increase in international business losses, which are expected to remain below Rmb2b as JD.com’s European expansion continues.
BUY (Maintained)
Current price:
Target price:
Upside:
HK$104.90
HK$148.00
+41.1%
Analyst
IMPORTANT NOTICE - DISCLOSURES AND DISCLAIMERS
This report is provided subject to, and must be read together with, the full Disclosures / Disclaimers available at this link, which are incorporated by reference into this report. In particular, this report is intended for general circulation and informational purposes only and does not constitute personal investment advice or a recommendation to buy or sell any investment product or security. You should independently evaluate the information and, where necessary, seek advice from a qualified financial adviser regarding the suitability of any investment. Analyst certifications required under applicable regulations, including SEC Regulation AC (where relevant), are included in this report. By accessing, receiving or using this report, you acknowledge that you have read, understood and agreed to be bound by the Disclosures / Disclaimers, as may be amended, supplemented or updated from time to time.
Related articles

17 Sept 2026
Trip.com (9961 HK) - 2Q26: In-line Results; 3Q26 Growth To Slow On Regulatory Pressure; Expect A Recovery In 2027

29 Sept 2026
Alibaba Group (9988 HK): APSARA Conference 2026 Key Takeaways

29 Sept 2026
